What is the Cost of Taking Social Security Too Early?

As part of your overall retirement plan, you’re probably counting on your Social Security benefits. But what happens if you miscalculate and end up taking the benefits too early? Couldn’t this short term boost help you if you’ve falling short in other retirement vehicles?
NJ-estate-planning-lawyer


A new study from United Income says that a couple electing for Social Security benefits too early could lose up to $111,000 over the course of their retirement. Given that people are living longer, deciding when to start receiving benefits is an important consideration that could have big impacts on your golden years.

The study found that only a very small portion of retirees-4 percent- took their government retirement benefits at the ideal point in time. To determine that optimal age, there are numerous factors that must be taken into account, including future retirement costs, being single vs. married, life expectancy, other sources of income, and whether or not the person intends to continue working.

Many retirees would get a big bump in their overall benefits if they waited until age 70 to claim, according to the study’s findings. Very few retirees are in a better position by taking these benefits prior to age 64.

Calculating the best age to claim SS benefits is a challenge for plenty of people. Thinking ahead about your retirement, however, helps you have an overall plan for accomplishing your goals in your own life and passing on your remaining assets to your loved ones, too. This can include working with professionals like an estate planning lawyer.

If you’re interested in the big picture, set aside time to talk to your CPA or other financial professional, your insurance specialist, your investment broker, and your estate planning lawyer so that you have considered the impacts of your accounts across the board.
What is a Fiduciary’s Job?

In your estate, a fiduciary has important legal responsibilities that must be addressed with the utmost level of care. Finding the right fiduciary is extremely important for protecting your interests and wishes.

A fiduciary has to provide the highest level and standard of care, not just because this is required by the law, but because the person establishing a fiduciary in a position of trust needs loyalty and honesty.

Fiduciaries might play multiple roles in a person’s life and estate. Common examples of people who serve as fiduciaries are bankers, attorneys, accountants, financial advisers, real estate agents, and business advisers. They must act in the best interests of the beneficiaries of a trust or estate.

A fiduciary can include a trustee, a guardian for your minor children, a personal representative or executor, or a surrogate/healthcare agent. Your lawyer also has some level of fiduciary responsibility in managing or helping with your affairs, too.

Since people in all of these roles can have a significant impact on your life or on the management of your estate, it is key to feel confident with your choice.

Most people want their estate to be transferred as painlessly as possible for their heirs. Choosing the right fiduciary is part of that conversation. Since your heirs might need to interact with the fiduciary like a trustee on a regular basis, you want someone that you not only trust but who can easily work with your loved ones and maintain open lines of communication and trust.  

Is Your Family Business Set Up to Succeed Beyond You?

A family business is something that goes far beyond a profit-generating venture. For you and your loved ones, it’s a source of pride and family connection. Which is why it’s important to make sure that proper succession planning has been incorporated in your long-term view of the company.

Did you know that there are three major reasons why family businesses fail? Two of them are directly related to how much forethought you put into the process of planning ahead. One is inadequate estate planning, which has ripple effects not just for your heirs but also for your company, and the other is lack of funds in place to pay estate taxes.

The third major issue affecting the future of a family business is the failure to properly prepare for the generational transition in the company, including who will take over key roles in the business.

While there are probably a lot of moving parts with your company and plenty of them that only you or your key employees are aware of, exit and estate planning might mean going outside of the office and getting the help of dedicated professionals.

This can mean working with an exit and succession planning professional, a CPA, a tax lawyer, and more. In most cases, your family business will have strong personal ties to your individual estate planning, and therefore all your tools should be created with both issues in the back of your mind. They must work together while you’re still part of the business and when you leave for maximum benefits.

How Much Does Experience and Knowledge Matter for Estate Planning Lawyers?

Not all lawyers are created equal, and finding someone to help you with your needs or individual case requires doing a little digging into the lawyer’s experience and past. All attorneys have a responsibility to provide competent client representation. This means thoroughness, legal skill, and the preparation and research involved in connecting a client’s needs with legal avenues and strategies.

A client must feel confident in the competency in the practice area of estate planning, elder law, asset protection planning, or business succession planning. Some attorneys will have more experience than others in crafting plans for specific client needs; make sure you ask a potential lawyer about how frequently they have represented clients in similar situations.

An attorney should also be prepared to turn down a case if he or she is not familiar with that area of the law and does not have the resources to properly help the client as necessary. A referral to another attorney or consultation with a different lawyer can help to ensure the client gets the support and resources needed.

An attorney should be familiar with the basic tenets of estate planning, but should also be involved enough with this practice area to remain aware of updates to laws and emerging strategies or technologies that assist clients with accomplishing their goals of protection, privacy, tax minimization, and more.

One of the most important things to remember when hiring an estate planning attorney is how well they understand your needs and put together a strategy based on what’s best for you. Speaking with a lawyer in an initial consultation is your chance to get questions answered and determine the course of action most aligned with your needs.

How Do I Grant Access to Online Accounts in My Estate Documents?

Any company with whom you have an online account probably has their own rules about how you can or can’t close or transfer on your account after you pass away. However, you might also wish to back up your plans for such a site in your own estate planning documents, too. How you list these is important for how the accounts will be handled.

In the event you want other people to have access to your online accounts once you’re no longer around, make sure you use the right language in your estate planning documents to reference lawful consent. This enables your account details to be properly disclosed to the people you choose.

Using a trust can help with this, since many modern trust documents include language authorizing the release of digital account details. You can talk with your estate planning lawyer about creating a digital access map so that all your online accounts are consolidated easily and have the relevant passwords stored there, too.

This process begins by you creating an inventory of all your important online accounts and which of these are password restricted. These could include:

  • The computer itself
  • Social media accounts
  • Online photo storage accounts
  • Email accounts
  • Bank and brokerage accounts
  • Online storage
  • Online electronic assistants and devices
  • Retail stores with your credit card information stored for easy purchase

It might take some time to pull together this list as people are living more complicated digital lives than ever before.

What Does Your Trust Actually Own?

When deciding what to pass on to your loved ones and heirs, proper titling is key to your wishes being followed in the manner you intend. Remember that some assets fall outside what is accomplished in probate, such as your life insurance policy. Regardless of what you state in your will, those wishes are overridden by the documents you’ve filed with the insurance company.

Senior couple with their financial advisor, going over their retirement income on her computer.

This makes it key to schedule an annual checkup in your calendar so you can verify that your intended beneficiaries are properly outlined there. You need the support of an experienced estate planning lawyer for matters outside of your beneficiary designations. Remember that the passing of your assets could have big implications for your loved ones, so this process needs to be approached with care and concern.

One of the most overlooked areas of titling assets has to do with a revocable trust. A revocable trust by its very nature can be changed and updated, but if you set up the trust and then promptly forget about it, this could cause serious issues for your family members intending to receive items inside the trust.

Make sure that if you wanted assets inside the trust for privacy and protection needs that you name the trust as the owner of those assets. All too often, setting up a trust excludes this vital follow-up step, and that can end up costing you significantly in the future. Set up a time to follow through on your trust after the initial setup so that each item inside is properly accounted for and so that you have peace of mind about the asset titling.

Do Americans Have Enough for Retirement?

Planning for your own future is one component of setting up your retirement plans. But have you also thought about how the assets you own will be passed on to future generations? Retirement is a two-way street.

According to a new study shared on CNBC.com, around 100 million Americans are currently covered by defined contribution plans. These assets are growing in value and are now worth more than $7.5 trillion. Most of this money is stored in 401(k)s.

What’s troubling about that study, however, is that the size in the accounts is small, especially when the age category is broken down to older Americans. Older Americans not only need to worry about living longer, but about having enough assets to protect them in the event of a long-term care problem.

The median amount in those retirement accounts was just over $58,000. The good news is that even with some drops in the economy, the average defined contribution plan increased by as much as 4 percent, since most people were putting aside more money. Furthermore, plenty of people are now choosing to automatically enroll in retirement plans than before, which experts believe is a key sign to increasing total retirement account amounts in general.

In general, the amount of money being saved is not enough to support people in their own retirement given some of the complexities of saving and living longer. Think ahead about what other strategies can be used to support your retirement savings and whether risk mitigation like long-term care insurance can help.

Speaking with an estate planning lawyer, a CPA, and a financial expert can all help you plan ahead for your own future.

Responsibility of Living in the Greatest Country in the World

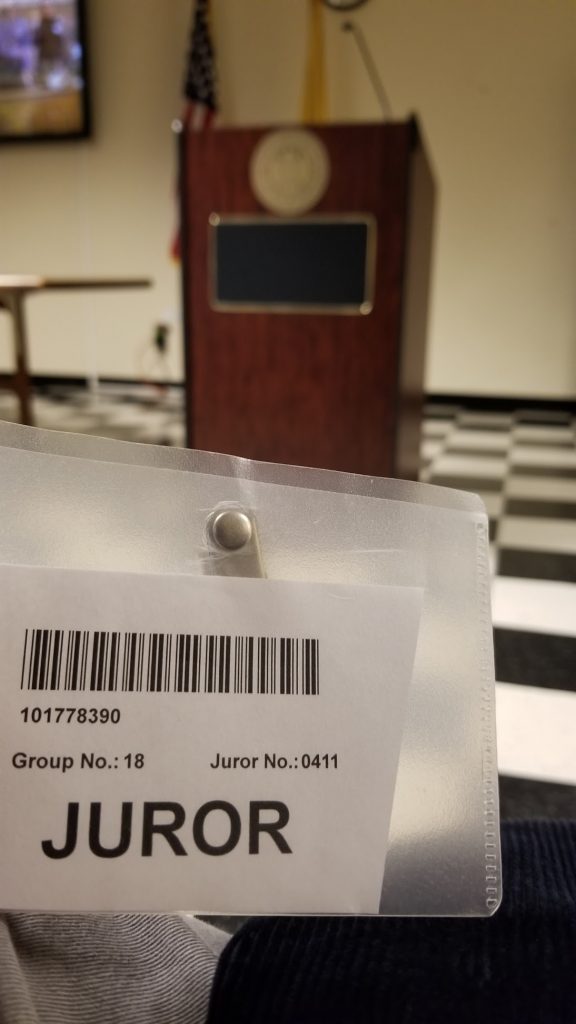
Over the last few weeks, I had the privilege of telling people that I was scheduled for Jury duty. Last Monday, I had to report to Middlesex County Superior Court for Jury duty at 8 a.m. in New Brunswick. 8 a.m. is early, especially if you are heading into a parking deck after battling route 18 traffic through East Brunswick.

Over the span of the several months that I had Jury duty scheduled, whenever I told people about it, the initial reaction I got was a look of sadness followed by, “But you’re a Lawyer, you should be able to get out of Jury duty, right?” Occasionally I would even get people telling me, “This is how you get out of Jury duty…” and they would proceed to share with me some funny ideas on how to get out of Jury duty.

Admittedly, Jury duty was not something for which I would volunteer. However, and I became more aware of this when I was there, it is a very important responsibility for the citizens who live in the greatest country in the world. In the end, I was not selected for a Jury. And I was relived – given the responsibilities I have for my family, for my clients & for my team. But what is everybody felt that way? No one would ever have their disputed heard by a Jury of our peers. We live in the greatest country in the world; this is our chance to do our part..

There are other parts of our lives in which we have responsibilities as well. For example:

  • When you have a family or a cause for which you care deeply, it is important that you choose what happens with your legacy.
  • When you have young children, you want to make sure that you meet your responsibility of taking care of them.
  • When you have adult children, your responsibility may be to leave behind a legacy or to protect your spouse against the cost of long-term care.

If we can help you to meet your responsibilities, please do not hesitate to reach out. I hope you enjoy the Articles below and remember: you are welcome to schedule a 15-minute call if you ever want to chat about those responsibilities.

How Much Will My LTC Cost?

If you’re already thinking about your healthcare expenses, you’re one step ahead of most people. But how do you know what’s enough to save, when you should invest in LTC insurance, and how to truly prepare for your LTC expenses? It becomes all to easily to push this topic off entirely, but you can’t afford to make that mistake.

Illustration depicting a sign with a long term care concept.

Planning ahead is key since most people over age 65 will need more form of long term care support in their older ages. Tasks of daily living might require assistance from an outside party- whether that’s a family member or someone in a nursing home or assisted living.

According to government studies, men will need this help on average for 2.2 years, while women will need it for 3.7 Most people have to turn to unpaid care from their family members, but given that more than one-third of people will need a nursing home at some point in their life, it’s important to think about the possibility.

The expectation that Medicare will help is a common misconception. Given that premiums for LTC insurance can be over $3,000, would you rather invest in LTC insurance or risk having your personal savings tapped if and when you need care?

The cost of a nursing home is substantial- if you have not talked over a Medicaid crisis plan with your lawyer, now is the time.

How to Manage Your Money Like You Have Plenty of It

There are many different secrets for millionaires, but one of the biggest is that they manage their money and their mindset about money differently from other people. Even if you’re not quite a millionaire yet, adopting a healthy mindset and orienting your financial and estate planning around it can have ripple effects in your life.

Accounting.

One of the first things that millionaires do differently is look towards the future with excitement and not anxiety. They know that tax laws can and do adapt, and they have plans and conversations with advisors by keeping this in the back of their mind.

It might surprise you to learn that many millionaires live below their means. Most of them believe that spending less than they can afford allows for savings opportunities and amassing more wealth that not only benefits their personal life, but also benefits their loved ones, too.

Millionaires take a very healthy approach to learning more about money. They are constantly interested in ways to do things better, which opens them up to having deep conversations with experts about whether or not a new strategy might be more effective. The very act of questioning can be extremely positive.

Finally, millionaires know they need help with their money and planning. They recognize that, even with a high volume of wealth, that the job of protecting it is theirs. So they keep an open eye towards potential threats, like the possibility of a disability or a lawsuit. Asset protection planning is a priority for people in this position.

If you’re ready to start thinking like a millionaire and taking your future into your own hands, schedule a meeting with an estate planning lawyer today.

The Power of Special Needs Planning & America’s Got Talent

This video has been making its rounds on Facebook and other forms of social media and, in my opinion, it is impossible to watch this without tearing up. For any parent, it is an amazing feeling to nurture a gift or a skill that your child develops and to ultimately see them perform at the highest level.

However, when a child has special needs, there may be a temptation to set the bar a little lower: the story of Kodi Lee is nothing short of jaw dropping. But it is also a testament as to what the power of love and nurturing can accomplish for any child, even a child with special needs. Kodi Lee is blind and has autism. However, with his mother’s love and family’s support, Kodi Lee accomplished what you are able to see in the video above.

All parents wish for their children to achieve their potential. If, God forbid, something did happen to the parents, either a disability or an incapacity, parents must plan to leave behind sufficient resources (money) to accomplish this goal. I hope you enjoy the video and I hope it inspires you. If you or someone in your life has a child or an adult with special needs in their life, please forward this video to them. And if they haven’t taken care of any planning, please encourage them to do so. It doesn’t have to be complex, but it does have to be done. Have an amazing day.

What Goes Into My Elder Law Plan?

Are you ready for retirement and beyond? People are living longer than ever these days, and that means you need a plan to help yourself or to enable loved ones to step in for action if you are unable to make decisions yourself.

A trust is one of the most critical documents in an elder law plan. This is a popular option because trusts avoid probate, unlike a will. Sometimes you might turn to your lawyer to help with an asset protection trust if you believe that your assets could be tapped by a creditor or if you believe that you could need Medicaid in the future.

Businessman notarize testament at notary public office

If you’re worried that your children or grandchildren might get married to someone who has their eyes on the inheritance you’ll pass down, a trust is also a valuable tool for ensuring that your loved ones get the assets, not someone else.

While all of these key documents help your family after you pass away, don’t forget about your own life. You might use a power of attorney to name the individuals who will make financial and legal decisions for you if you are unable to make them on your own.  A power of attorney can also be used with a trust to give you additional protection, especially if you’re worried about the possibility of a guardianship proceeding by the courts to determine who should take care of you.

You might also have other unique needs, like real estate or concerns about your spouse’s health, that should be discussed with your elder law attorney in detail. Both of you can create a plan for how you’ll protect your own life and the assets you intend to pass down, which gives peace of mind for all involved.

What Does It Mean to Pay for Long Term Care with a Combination of Assets?

Most people haven’t set aside significant savings for the sole purpose of paying for their long term care but long term care expenses can have catastrophic effects on your savings, especially if you’re a partner with a spouse who might need to rely on these savings for the remainder of his or her retirement.

Many people need to invest in the process of doing strategic long term care planning to discuss the benefits of various types of ways to pay for long term care services. It’s estimated that more than two thirds of people above age 70 will require some form of long term care services that will range from between one and three years.

This could decimate an individual or a couple’s retirement planning savings and therefore, should be factored into conversations about Medicaid qualification and other assets. In many cases, people use a combination of different types of assets to qualify for long term care expenses. Personal savings gives the most flexibility when it comes to selecting options for long term care. Personal savings can be used for nursing homes, in home care, assisted living or adult daycare.

But this is a long term option for very few people due to the high cost. Veterans’ disability benefits can be used for any long term care services but non-disability benefits extended to veterans cover in home services and adult daycare while not rent at an assisted living facility and are therefore, more limited. Sometimes a loved one might turn to a reverse mortgage for long term health care needs and the money is then repaid when the home is passed onto an heir or sold.

Medicare will pay for very little of long term care and under limited condition, including skilled nursing care in a facility. Medicaid is a last resort but one that many people end up needing. In fact, in 2018 Medicaid accounted for 62% of nursing home residents. Schedule a consultation with an estate planning attorney today to learn more about how this could affect you.      

Does Medicare Pay for Long Term Care Expenses?

Far too many families find themselves in the position of realizing that Medicare doesn’t pay any or very little of the long term care expenses that can emerge when a loved one suddenly needs to enter the nursing home. Caring for a loved one at home might not be an option for your family. It may become stressful at the beginning and eventually become completely unmanageable.

Social Security card and Medicare enrollment form

If you are able to afford it, an assisted living facility is one optional solution. However, many people don’t have the financial means necessary to put a loved one in assisted living. One of the best protections against the rising cost of long term care and health expenses in older age is long term care insurance, but too few people know about it or have an active policy that could help them in the event of a sudden disability or long term care event.

Medicaid is another planning option but you must ensure that you have a Medicaid strategy and plan in place. This is because Medicaid has specific requirements about what it fully takes to meet the grounds for eligibility. Most people have no idea how the Medicaid process works. According to the US Department of Health and Human Services, up to 75% of Americans aged 65 and above will need long term care for a period of between one and three years, but fewer than 30% of Americans over age 40 have set aside any money to pay for it.

This could be a catastrophic mistake for you and your loved ones if something suddenly happens to you and you are unable to care for yourself. It’s better to set aside time to speak with an experienced estate planning and Medicaid planning attorney today to learn more about how best to protect yourself.      

New Retirement Study Shows Importance of Getting Financial Help

A new study has found that the retirement savings rate significantly improves when employees and workers get help with the bigger picture of their financial life. Employees who had access to ongoing coaching and insight for all aspects of their financial lives saw a retirement plan contribution rate increase up to 9.4% of their pay in 2018 when compared with 2013 numbers of 6.3%.

The words Retirement Plan circled in red with a list of saving and debt obligations surrounded by graphs, charts, books and pencils.

Those who reported being on track to achieve their retirement planning goals also jumped from 21% in 2013 up to 57% in 2018. This makes it even more important for workers to understand how to get advice about all money related matters. The study looked at more than 2,400 employees who had access to coaching. Financial wellness also improved during the five year period that they received personalized assistance.

The employees with the greatest levels of financial stress have foundational level issues, such as building an emergency fund, issues like cash flow and debt management. Having a bigger and better perspective on your entire financial life and including estate planning and other important provisions can help you to feel more confident about your future. Schedule a consultation today with an experienced estate planning lawyer to talk more about how retirement plan is a part of your overall estate plan and what it can mean for you as well as your beneficiaries.      

How Can I Tell If A Will Was Revoked or Replaced?

Creating a last will and testament is an important component of estate planning, but it can also be one of the most confusing aspects of probating or administering an estate.

A will does not expire but identifying different versions that replaced an older one or finding a will that at some point was revoked can be very important to heirs and beneficiaries.

Finding a binding and valid will years after another one was really created, could revoke certain provisions and lead to different estate circumstances.

Whether or not a will is valid could alter over time based on the property and the assets of the estate owner. The estate owner might have to create a new will with updates to ensure that an agent will execute the wishes of the person after he or she passes away.

Terminal patient talking with notary about his last will

A revocation or a replacement will could be used to alter plans significantly. Once the new will is created and valid, the previous will is no longer viable.

Plenty of estate owners will make updates to their will based on changes in the estate that occur over time, such as bank account, property holdings, investments and other assets within the estate. Others might put liabilities in the will. It is important to understand that as the writer of a will, you have a responsibility to be directly involved in revoking the previous will. You can explain your intention to revoke the will or revoke it physically by destroying it. Scheduling a consultation with an experienced estate planning lawyer could be the first step towards figuring out what to do when you have an existing will in place and intend to change it.

Preparing Your Online Accounts for What Happens When You Pass Away

If you’ve already taken the diligent step of getting your general estate plan in order, is it possible you have neglected your online accounts? Today it is easy to feel like you’re adding new online accounts every week, trying to keep track of all of the passwords and related information.

Senior couple working out their bills at home in the kitchen

The problem is that when you pass away, you might not have taken the right steps to close those accounts out. This means that there can be a whole range of problems, from a loved one who unexpectedly sees an annual friendship reminder and is affected by grief all over again to the possibility of ghosting, which is what happens when someone steals your personal information after you’ve passed away and uses it for identity theft purposes.

You’ve put a lot of time into curating and collecting your online accounts. You might want loved ones to be able to download pictures or other materials, or perhaps you’d like your account closed altogether. If you have any opinions about the future of your online accounts, you should consider writing these down and checking with the individual policies with each account to make sure you’ve covered all your bases.

For loved ones who don’t have the passwords, it might be difficult or impossible for your accounts to be closed down after you pass away. It might seem concerning to create a list of all your usernames and passwords, but rather than keeping this at home, you might store it with your final will and other instructions you want your family to see right after you pass. This can be stored in a safety deposit box or somewhere similar for safety and this can still give you the peace of mind that someone can step in to manage or close your accounts if you wish.

If you need help adding your digital estate to the rest of your documents, schedule a time to sit down with your lawyer today to talk options.

Are You Falling for This LTC Myth?

Whether you’re concerned about your own health issues in older age or are now taking care of parents with issues, you might be under the impression that Medicare is in place to cover the vast majority of needs. This is not true, and it can come as an unwelcome surprise when you’ve already counted on it in your mind.

Long Term Care Word Cloud on White Background

LTC expenses can be significant. And if you don’t know how they’ll yet affect you, it’s easy to push that off as something to worry about in the future. But by the time the future arrives, most people haven’t done any planning and instead are self-funded.

Self-funding with LTC means that any income or savings you personally own gets tapped into first as a means of paying for your care. Given that the expenses for LTC can run from $50,000-100,000+ per year, this can be a substantial portion of your savings.

If only one spouse needs LTC, this also means that the other spouse is at risk of not having enough assets left behind to care for themselves. This can turn into a downward financial spiral that is difficult if not impossible to stop without some Medicaid crisis planning.

But you don’t have to wait until someone is in need of a nursing home to plan ahead for the possibility. Instead, you can set aside time to speak to an estate planning lawyer today to learn more about your options with LTC and to discover strategies you can put into place today to make a big difference. Talk to a lawyer today to learn more and get started.

I’m a Single Parent. What Do I Need to Know About Estate Planning?

Being a single parent puts you in a position of power and responsibility that makes it all the more important that you tick off those important adulting activities like estate planning. These are some of the most important decisions that an adult can make and they can have a clear impact on your minor loved ones.

Good looking woman teaching her little cute girl to cook with some cookware in the kitchen

In deciding how to pass on your assets, your parental expectations and your evaluation of the child’s potential to meet these expectations can determine whether or not you might decide to limit access to funds and under what conditions those limitations can be removed. For single parents who have a minor child, this means that the parent must step into a leadership role to accomplish estate planning. When one part of a couple passes away, the child or children typically do not have to leave the school, home and community. However, things are different when a single parent passes away.

A child can leave that city to live the former spouse or with a different relative, leaving behind friends and familiar locations. This makes it even more important to understand your approach to these other adult relationships and who might be put in a position of authority should something happen to you and you need support for your minor children.       

What is a Letter of Intent?

If you’ve ever thought about estate planning before or even put together some of the key documents, you might still have questions about how to minimize the chances of an estate planning dispute after you pass away.

Writing letter to a friend.

One popular tool for addressing this issue is to put together a letter of intent. Along with your other estate planning tools, writing a letter of intent can help to reduce the chances that anyone in your family or estate administration process does not understand the purpose of the tools you’ve selected.

A letter of intent is a document left behind for your beneficiary or executor. The purpose of the letter is to clarify what you want to happen with a certain asset after you become incapacitated or pass away. Other letters of intent provide details about funerals or other special requests you might have about the management of your estate.

This document might not hold up as valid the way that a will or trust does, it can help to explain to a probate judge what your intentions are and this could help in the distribution of your assets if the will is determined to be invalid or if there are challenges regarding what’s inside the will.

If you are passing down various assets of different levels to your family members, a letter of intent could also be your opportunity to explain why you made the decisions that you did. Your letter of intent should always be written with the support of your estate planning lawyer.