How to Avoid Tax Consequences While Leaving Behind An IRA

It may have been in the best of intentions that you decided to leave an IRA behind to a loved one but this can generate unintended tax problems for the beneficiary. Naming a trust as a beneficiary of your IRA instead can help to protect heirs who are disabled, vulnerable to creditors or who are minors.
Failing to appropriately structure your trust, however, could accelerate IRA liquidation, which could cause significant problems for taxable distribution. Trusts only need to have $12,750 in 2019 to be subject to the top tax rate of the 37%.

When it comes to naming a beneficiary for your retirement account, it’s well worth scheduling a consultation with an estate planning lawyer. By using a trust as your IRA beneficiary, this still enables you as the owner to have some element of control. However, not every IRA custodian will enable you to list the trust on your beneficiary form. Furthermore, this can be complicated by the tax code. There are specific conditions for trusts that are serving as beneficiaries for retirement accounts. Failure to follow through on these rules properly could lead to an accelerated distribution of the IRA assets and significant taxes.

This is why it is recommended that you partner directly with an experienced estate planning lawyer who is very familiar with establishing a trust as the beneficiary of an IRA to avoid consequences to protect your underlying goal of passing on assets to your loved ones.      
Is It Safe to Use A Template for A Last Will and Testament?

Deciding to plan ahead for the future often begins with using a last will and testament, but a simple internet search might make it seem as though all you need to do is print out a form, fill it out, and file it away.

A blank last will and testament form with a pen laying over it.

This has numerous potential pitfalls, including the fact that the template may not be accurate for your individual state or needs and this fails to include the possibility that you might need to update your estate plan in the future based on changing circumstances in your individual life.

Because of all of these issues, it’s important to schedule a consultation with an estate planning lawyer who is familiar with how to craft a proper will and testament, and to continue to keep it updated over the duration of your life for your individual needs. Of course, one of the biggest reasons that people will consider using their own last will and testament template is because of the cost. It is certainly the truth that it will be more expensive to hire an attorney to put together your last will and testament for you. However, this money goes a long way in giving you peace of mind.

Those who believe that simplicity is the name of the game in their estate plan might turn to these templates as a meaningful way to pass on their assets to future generations. However, if there’s any complexity in your estate plan, or you require customization, it’s far better to partner directly with an estate planning attorney. Many of these templates are not updated for your individual state and fail to incorporate updates in state and federal tax laws.

 This makes it even more important to retain the services of an estate planning lawyer you can trust.      

Unequal Gifting More Common, Study Says

Increasingly, clients are turning to estate planning lawyers to help with the process of gifting unequal shares or assets to their children. There are several different reasons why a parent today might look to outline these kinds of specifics in an estate plan, but it’s also happening at the same time when family conflict poses the biggest threat to a successful plan. 

Portrait Of Frustrated Couple Sitting On Couch Quarreling With Each Other

The study, from Merrill Lynch, found that parents who have more than one child are at least considering leaving unequal shares. According to that study, two-thirds of Americans believe that an uneven split is likely more in line with current family dynamics. 

Sometimes it’s the concern about a child’s spouse and how those assets could be affected through a divorce. In other cases, the parent believes that one child is a spendthrift and the other is more responsible. With a family business or cherished family home, geographic location and desire might factor into the decision, too. 

An unequal inheritance can raise red flags, depending on how or if the parent communicates their intentions. For example, another study found that when it came to siblings who argued over money in their adult lives, over 70% of the time the root cause was the way that an inheritance was divided. Those children who did not receive what they felt were equal shares have chimed in with other research projects about how unfair it was. 

You have to choose a model that works to address your concerns and goals for your assets and your loved ones. In this case, fair does not always mean equal. 

If you’re trying to decide what’s right for your family, talking to an attorney can help you to clarify some of your individual goals in the estate planning process. No matter how you want to split up your assets, tactics in an estate planning and asset protection planning toolkit can become an important component of defining your legacy. 

Is Family Conflict Blocking Your Estate Planning?

Market volatility and the possibility of further estate tax reform all have many estate planning advisers prepared for sudden shifts in strategies, but those aren’t even the issues at the top of the list for most American families.


Young Afro-American family fighting in kitchen because of an affair. Man in glasses holding mobile phone, pointing finger at screen, trying to explain himself for love messages from unknown woman

In fact, a new TD Wealth study confirmed last year’s findings that family conflict is the biggest impediment to successful estate planning. More than 100 respondents were included in that study, many of them professionals in the retirement, estate, and investment world.

More than half of respondents in the study said that trying to navigate current family dynamics and possible future dynamics was a major challenge that required new tools and top tier communication.

The challenges of blended families and loved ones who failed to communicate their plan to the other family members are some of the biggest challenges still faced in estate planning.

Even when a person pulls together a comprehensive plan to address their assets and to protect their family, figuring out who gets what and whether that should be communicated to everyone are common concerns.

Telling loved ones about an estate plan could even spark further controversy for those family members who feel left out or who don’t understand the reasoning behind the planner’s approach.

Are You Looking at Retirement Planning Backwards?

Retirement planning and estate planning should work hand in hand, and while plenty of people have admitted in recent studies that they don’t have the basic tools of an estate plan such as a will or trust, a 2018 study conducted by Northwestern Mutual found that many Americans feel they have inadequate retirement plans.

Retirement planning and estate planning should work hand in hand, and while plenty of people have admitted in recent studies that they don’t have the basic tools of an estate plan such as a will or trust, a 2018 study conducted by Northwestern Mutual found that many Americans feel they have inadequate retirement plans.

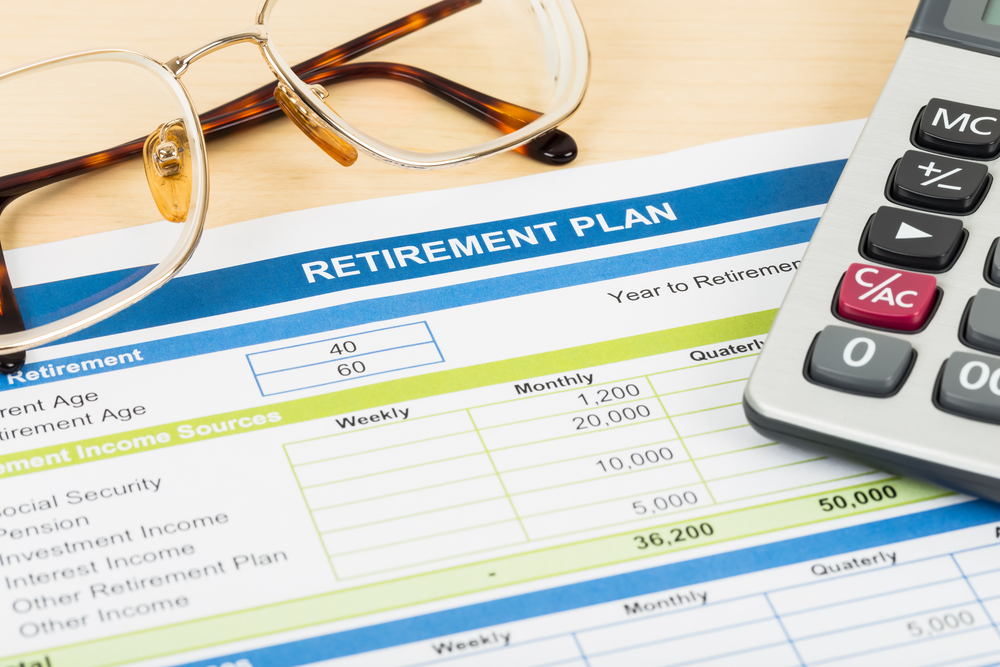
In fact, 70% of respondents said that they felt they hadn’t done enough for planning for their retirement. To avoid falling in the trap of getting into financial difficulty too close to your retirement age, choose to plan backwards instead. Many people plan backwards to accommodate their individual situations and lifestyles. This starts by considering the amount of annual income you might need during your retirement. Then you will want to decide what kind of life you hope to achieve in retirement and what kind of price tag might be associated with it. Since this answer will be unique for everyone, it’s important to come up with your own solution and to plan backward. Some people want to spend time at home with loved ones and helping to raise grandchildren, whereas others would be focused on travelling extensively. Think about the possible costs of all these social activities and hobbies, and don’t forget about the possibility of a high price tag that can come from long term care and health events that occur later in life. Having appropriate planning done well in advance can help you to enjoy a retirement as you intended but failing to incorporate health care planning such as ways to pay for it, Medicaid planning options and having powers of attorney to enable another person to step in and make decisions on your behalf could all compromise your ability to be successful.     

[End of transcript]

What Questions Should You Ask Before Selecting a Legal Guardian?

Most parents recognize that one of the most powerful aspects of putting together a will is establishing a legal guardian. This is the person who is legally eligible to care for your child if something happens to you and the selection of a legal guardian is a highly personalized decision that must be taken carefully.

Female hands with word guardianship on blue background

This is a person who will make decisions about your child’s schooling, health and overall upbringing. This means that not only does the person you select need to be comfortable with playing such a key role in the child’s life, but you must be comfortable with your selection of this individual. Doing so requires answering some key questions, such as:

·      What are this person’s moral and religious beliefs? Do they line up with my own?

·      Is this person up to the challenge of raising my children?

·      Does this person love my children?

·      Does this individual have any medical conditions that could prevent them from serving effectively as a guardian?

·      Does the potential guardian have access to financial resources to care for my child?

·      Will my child still be able to have easy access to their other relatives?

·      Where does this person live and what is this individual’s home situation?

After you have answered these questions and selected someone to name as a guardian, it is critical to discuss it directly with him or her. While many people will be flattered that you even considered them to serve in this role, others might not be willing to accept the responsibility. You might consider choosing an alternate guardian as well.  

What Are the Advantages of Using Will Co-Executors?

Provided that you have selected co-executors or one or more individuals to serve in the same role can get along and cooperate, co-executors provide numerous benefits for the purpose of your estate planning. These include:

•               This can avoid making it seem as though one sibling is favorited above another.

•               If you are not sure that you can trust any individual person to serve as the executor, co-executors have a legal duty to one another to keep each other honest. Be aware, however, that co-executors who might not fully trust one another could increase the possibility of disputes and conflicts down the line.

•               The co-executors can divide up the work.

•               The co-executors may have one another for support and consultation if questions arise.

•               If you already have an established business, a co-executor who is familiar with business matters and management can work alongside another executor such as a spouse to ensure that you have addressed all major issues.

•               Each co-executor might bring their own unique talents that apply to certain respects of the estate.

Think carefully about whether two executors is the right choice for you.

Dying man signing his testament in the presence of notary

Only an attorney can help you understand whether or not it makes sense to use co-executors. Co-executors should be approached with caution, but the support of an experienced attorney is instrumental in helping you to determine your next course of action.     

How Can I Create A Power of Attorney?

Most people would first turn to an online process to assist with the drafting of a power of attorney, but this is not recommended. State laws vary in terms of how to establish a power of attorney and because of the specifics in the law, it is recommended that your document is executed in accordance with state laws.

Close-up Of A Person Holding Pen Over Power Of Attorney Form

This can be done by scheduling a consultation with an estate planning lawyer. Prior to generating a power of attorney, you need to do some thinking. what aspects of your life do you want an agent to be eligible to handle. Furthermore, you must approach the process of selecting the agent thoughtfully.

This is because this person will be in charge of your affairs as outlined in the power of attorney, especially if you become incapacitated. Establishing a power of attorney document also requires coming back to it over time.

At least once a year, you need to make sure that your POA document still reflects your wishes.

Knowing that someone else will be able to step in and handle your affairs and knowing that this person is selected by you rather than the court can give you a great deal of peace of mind but putting together your own power of attorney document exposes you to the possibility of making mistakes. This means that you should instead speak directly with an estate planning lawyer to verify that the language inside your power of attorney document is accurate.     

Can I Remove a Trustee from a Family Trust?

There are many different reasons why you might wish to revoke a trustee’s powers. If you put together a family trust yourself, or if you are a beneficiary or a trustee of a trust, there might come a point in time in which you believe that a trustee needs to be removed.

3D illustration of FIDUCIARY title on Legal Documents. Legal concept.

A family trust offers many advantages to a person who establishes it and the beneficiaries of that trust, such as tax benefits, long term care planning strategies and probate avoidance.

However, this is a complicated fiduciary arrangement that can lead to conflicts between beneficiaries and trustees. The person who creates the trust then transfers assets inside the trust. At that point the trustee manages these for the benefit of designated beneficiaries. A trust agreement might state the circumstances under which a trustee could be removed by the creator.

Trust agreements will typically allow a trust creator to remove a trustee, including someone who is originally named as a successor trustee. The trustee does not have to be given a reason for the removal in most cases. Instead, the trust creator would execute an amendment to the trust agreement. In an irrevocable trust, however, the creator cannot become a trustee. Therefore the trust creator has to give up the right to revoke the trust and to serve as a trustee.

Sometimes removal can occur by beneficiaries or co-trustees. State law provides guidelines about a trustee’s responsibilities and duties, particularly when that person allegedly violated his or her fiduciary duty.

Is It A Good Idea to Attempt to Disinherit A Child?

You have the power to disinherit any or all of your children regardless of what state you live in, so long as you expressly name these terms in your estate planning materials. If you fail to mention a child specifically in your individual will, that child could still maintain a legal right to claim a portion of your property depending on your individual state laws.

Upset adult daughter ignoring not listening to senior old strict mother in law arguing moralizing scolding controlling showing authority to stubborn young woman, different generation conflict concept

If you want to disinherit a child, you will need to sit down with your estate planning lawyer and discuss how you intend to do this directly. One of the leading ways that many spouses choose to approach this situation is to leave all of their property to the other spouse, while naming children as alternate beneficiaries.

This helps to protect and minimize the chances that someone could allege that a child was overlooked. There is no legal requirement that if you intend to disinherit a child you must explicitly state this inside your will, but you can if you wish to do so.

A consultation with a knowledgeable estate planning lawyer can help to illuminate you about many of the key issues involved in passing on the property or disinheriting a child.      

How to Use A Limited Liability Company for Asset Protection Planning

When consulting with your estate planning lawyer about putting together an LLC for tax and business purposes, one of the most common reasons for doing so is asset protect. A major goal of asset protection planning is to move assets into a strategic tool, such as a trust, to eliminate or reduce any exposure to liabilities.

This has to do with protecting the individual from liability overall, financially and with their estate plan. Special care must be given to transfers that are done for the purposes of avoiding creditors. Some of these could be classified as fraudulent if you don’t have an experienced asset protection planning attorney to help you.

A practitioner in the field of asset protection planning law is in a strong position to help identify the asset protection planning strategies necessary and to recommend implementation methods.

The formation of an LLC is one of the most popular ways to address asset protection planning and is often recommended before an individual purchase a partial of commercial real estate.

The purpose of establishing an LLC could be to prevent the client from being exposed to individual liability. Restructuring the holdings to engage in asset protection planning could be a conversation to have with your estate planning professional.

Transferring assets inside an LLC can protect the assets from future claims from creditors who are attempting to take that money from the LLC owner. If you have questions about the process of asset protection planning, schedule a consultation with an attorney today.

How Does the Uniform Transfers to Minors Act Impact Your Estate Planning?

Through the Uniform Transfers to Minors Act you can leave gifts behind for your child or any minor in a living trust or a will. This law has been adopted in practically every state across the country. The property manager for a child is known as a custodian and under the UTMA.

happy grandma with grandson embracing outdoor

The custodian’s management role ends when the minor achieves age 25 or 18, depending on the specifics of state law. In your living trust or will, if you intend to leave a gift with the UTMA, you’ll identify the property and the minor that it is being left to.

It is then your responsibility to appoint an adult custodian for supervising this property until the child reaches the age that he or she must receive it. In the event that your first choice for custodian is unable to do the job, you can also name a successor custodian. Bear in mind that the selection of custodian is important because this individual has tremendous discretion to use and control the property in the child’s interests.

The custodian has the right without court approval to manage, invest, re-invest, collect and hold this property, and to spend as much of it as the custodian deems advisable for the use and benefit of the minor. A custodian is not responsible for filing a separate income tax return and is entitled to reasonable compensation paid to him or her from the management of the gift property.

The custodian is not required to be under the thumb of court supervision. Every gift made under the UTMA can be made to only one minor with only one individual named as custodian. When the child who reaches the termination age, he or she will receive the remaining balance of the gift.

Make sure that you sit down with your estate planning lawyer to discuss the termination age in your state and other specifics of making a gift through the UTMA.        

What is a Child’s Trust?

In a child’s trust, you are eligible to leave behind specified property to one child. This property will be held distinctly from any property left for other children. You might choose with the help of your estate planning lawyer, for example, to create a child’s trust for each child if you have more than one.

The trust is your legal entity through which an adult, also known as the trustee, is responsible for handling property or money for someone else. In this case, the trustee is responsible for managing the property or money identified for a minor child.

In the event that you create a trust, the property manager is known as the successor trustee or the trustee. Your trust document should only be created with the help of an estate planning attorney because it serves the important role of sitting out the trustee’s responsibility and the rights of the beneficiary.

A will or a living trust are other tools that can be used in conjunction with a child’s trust. If you create a child’s trust as part of your living trust, the property placed inside avoids probate. With a child’s trust, you can also select the age that the beneficiary must achieve before the trust property is turned over to him or her.

This is frequently used when a large amount of money is being left behind for a child and the parent has concerns about the child’s ability to manage it appropriately. They might not want the child to receive the property outright until he or she has achieved an age of maturity such as 30 or 35. As with other trust planning procedures, the control of this document is up to you and you have a great deal of flexibility in deciding what works best for your individual family. Speak directly with an estate planning attorney about how to use these tools.        

What Is A Residuary Beneficiary?

Selecting your primary and alternate beneficiaries is the first step to determining who will receive your property when you pass away. Outside of your will and trust, certain property passes directly through beneficiary designation forms, such as the proceeds from your life insurance policy and your brokerage accounts. Many people are not familiar with the concept of residuary beneficiaries.

Close-up of a fountain pen

Residuary beneficiaries should be named in your living trust and your will. A residuary beneficiary is a person who receives all property left under a document that is not received by anyone else, either because the person named did not survive to inherit it, or because no beneficiary was named for that property.

The residuary beneficiary can be thought of as like a backup, so it is one way to ensure that your property goes to someone you choose rather than someone the court chooses. The residuary beneficiary you name in a living trust will only get any trust property that is not specifically designated for other beneficiaries. Inside a will, your residuary beneficiary will get all of the property that is not left to another person or entity through any other method.

The residuary beneficiary does not have to be sought out as only a backup, however. Certain people leave all of their property to a residuary beneficiary and others will leave most to the residuary, naming specific gifts for a few primary beneficiaries. It is always good to have an alternate residuary beneficiary after you name the first person in the event that he or she is unable to accept this property due to passing away.       

Do I Need to Inform My Beneficiaries That They’ll Be Receiving Items from My Estate?

After you’ve crafted an estate plan, how do you feel about telling some or all your beneficiaries that you have left property behind. Does it matter whether or not you tell them exactly what you’ve left them? There are not any laws requiring you to inform your beneficiaries anything about your decisions.

You can provide for your beneficiaries without informing them at all. You might decide that there are good reasons, such as the possibility for family conflict that will lead you to decide not to reveal how you’re leaving your property. Letting your beneficiaries know what they’ll receive, however, gives them some peace of mind about the future and can help your loved ones plan ahead.

Happy family with husband, wife, child, grandfather and grandmother choosing food and drinks in bar

In many cases, however, informing beneficiaries of what they can expect to receive from your estate only serves as the basis for more family conflict. If siblings perceive that another member of the family has received more than their fair share, this can lead to conflict while you’re still alive, or even challenges to your existing estate plan after you pass away.

You might want to discuss with your estate planning attorney whether or not it makes sense to inform particular beneficiaries about what they can anticipate. With sentimental family heirlooms, your loved ones may have specific requests, and you might wish to honor these by not only naming these in your estate plan but informing the beneficiary that he or she can expect to receive it when you pass away. Be aware of the possible consequences, however, of sharing with only certain members of the family and excluding others. This approach in and of itself can also lead to family conflict.       

Should I Name A Couple as Co-Guardians of My Minor Child?

A will is the official estate planning document that you can use to name a guardian for your minor child in the event that something happens to you or you and the other parent. In many cases it can be tempting to name a couple as co-guardians. However, this is a poor idea to name more than one individual to serve as a guardian for your children.

Two children going in spring green field

This increases the possibility that those two people might disagree about the best way to raise a child. However, there is one specific situation in which it makes sense to name a couple as co-guardians. This is when you want to name two people to care for your children together.

For example, if you know another married couple that understands the implications of being named as guardians, and is comfortable serving in this role, this couple can act as the child’s surrogate parents. Both of these individuals will be allowed to do things for your child that would require legal authority, like taking them to a doctor’s appointment, or picking them up from school.

When you do choose to name a couple as co-guardians for your minor child, you must understand that these individuals have to agree on what is best for the children. Any critical difference of opinion between these two people would require intervention of the court, which could amplify the conflict and concerns expressed by your children.

If you name a couple that decides to get divorced while you are still alive, you need to schedule a meeting with your estate planning lawyer to revise your will, to name one or the other or a different person altogether to step in as the guardian of your minor child.

Select a couple that has a unified parenting style, is likely to stay together a long time and is capable of making joint decisions without conflict if you firmly feel that this is the best choice for you and your child.      

What Is A Primary Beneficiary?

The word beneficiaries can be confusing, but it refers to institutions or people that you intend to leave property to. There are a few different types of beneficiaries including residuary beneficiaries, final beneficiaries, alternate beneficiaries, life estate beneficiaries and primary beneficiaries. Primary beneficiaries are those that you leave identified gifts of property to and usually involve a specific piece of property.

Primary beneficiaries can also be named for different items. Some people choose not to name primary beneficiaries at all, instead leaving all of their property to residuary beneficiaries. Residuary beneficiaries are those who receive property left in a trust or will that has not been specifically left to other beneficiaries.

Life Insurance Form Application Security Concept

Alternate residuary beneficiaries can also be named. Alternate beneficiaries are those individuals who can receive property items if the primary beneficiary is unable to receive it or has passed away. Life estate beneficiaries mean that an individual has certain rights to receive income from or the use of the property during their life, but never to become a full legal owner of the property.

Final beneficiaries are those who are eligible to inherit a piece of property after a life beneficiary passes away. Establishing both primary and alternate beneficiaries is recommended for each piece of individual property that you intend to pass down using a trust or a will. This is because you can avoid many confusing aspects of estate or probate planning, and can ensure that you have expressly considered each item most important for you to name.        

[End of transcript]

Understanding Joint Tenancy

There are several different types of shared ownership when it comes to property. One of these is known as joint tenancy. Property that is held under a joint tenancy includes a written ownership document that identifies the owners as joint tenants with right of survivorship or as joint tenants.

Joint Tenancy Agreement Property Renting Estate Concept

Each tenant owns an equal portion of the property and the share of the first individual who passes away will go to survivors, even if there is a living trust or a will that has contradictory terms. Joint tenancy can only be created through a written document.

If you currently own property using the phrase joint tenants with right of survivorship, there will be no question about the portion of ownership that you have. The answer to whether or not something can be classified as joint tenancy depends on the state in which the property is located.

Make sure that if your current document says that you hold ownership with another individual using the term ‘or’ or ‘and’, you need to ensure that you have had this reviewed by an estate planning lawyer regarding the specific rules in your state.

The specificity of the writing in these documents is instrumental for outlining whether or not you have shared ownership.        

Considering Your Digital Legacy

When you’re making a comprehensive plan for your estate property, don’t forget all of the materials you have stored online, such as digital files, your social networking identities and access details, your accounts and your blogs.

Smiling young man analyzing his expenses and paying online

While you may not be able to line item each of these items through your will, you may still want to consider what will happen to them in the future. Here are some of the most important questions you need to consider in the process of evaluating your digital legacy:

  • Do you want your Facebook profile to be put into memorial status, left alone or deleted?
  • Do you want someone to make any final entries on your blog to notify individuals of the future of the site?
  • Do you want someone to have access to your email accounts after you pass away?
  • What should happen to the future of your domain names?
  • Do you have any online communities, such as a Facebook group that should be notified about your passing away?

Many people overlook these aspects in the process of estate planning, but as things in the world have become increasingly digitized, it is extremely important that you do everything you can to discuss your options with the help of an experienced estate planning lawyer.

If you want your survivors to be able to log into your online accounts as users, make sure that your final instructions left behind include login names and passwords. Your estate representative may be able to have limited access to your account, then this can be helpful if you choose not to leave login information.        

New Study Shows That Extremely Wealthy Americans Are Getting Younger

The old estate planning myth is that people don’t need the help of a knowledgeable estate planning attorney until they have amassed significant wealth or are in their older years.

smiley successful couple with umbrella standing under money rain

This is a myth because everyone can benefit from the process of going through estate planning and discussing options directly with an attorney. All too often people realize all too late that their loved ones have been left to suffer the consequences of failure to carry out estate planning.

New studies show that younger Americans are amassing more significant wealth, and this highlights the need for advanced estate planning services such as asset protection planning. Since 2014, a survey of American investors who had $25 million or more in their possession determined that the average dropped by over 11 years.

The average age of a U.S. investor who has at least $25 million dropped to age 47. This indicates a significant generational transfer of wealth that could be beginning.

Although the sample size of this study was small, it could hold important implications for the future of estate planning. Individuals over age 65 currently hold more than one-third of U.S. wealth.

That number has not grown as quickly as the proportion of elderly Americans in the population. If you are contemplating putting together an estate plan that protects your wealth now and into the future, schedule a consultation with a lawyer today.