Give Plenty of Attention to Your Life Insurance Trust

Are you contemplating using a tool such as an irrevocable life insurance trust? You need the support of an attorney who has helped many other people. Craft these trusts before to ensure that all of the provisions appropriately protect you and are legally valid. 
Simply put, estate plan attention must be given to your irrevocable life insurance trust. If someone has joint trustees listed on an ILIT, one common question brought forward by clients is whether or not the beneficiaries will be able to keep those funds out of the estates of beneficiaries. While this may seem like a cost-effective step to list two of your children on the ILIT before the second death, it is important that everyone understands the requirements of being a trustee and how to appropriately accomplish them. It might also be beneficial to contemplate transferring the trustee powers to a third party, assuming that the beneficiaries intend to access the funds for their own purposes.

If not, the IRS may determine that this is actually a trust fund inside the personal estate of the beneficiaries. A consultation with an estate planning attorney can go a long way towards addressing issues and questions you may have over the duration of the process.
Don’t Allow This Mistake to Swallow Thousands of Dollars Out of Your Estate

The estate tax exemption is currently set at multiple million per person. While conventional planning techniques, at a very basic level, can cover you from a tax perspective, they might not address the family conflicts, and in particular, one of the leading mistakes that people make when looking ahead to their future is in appointing the smartest or perceived brightest child to oversee your estate. estate-plan-NJ

This could end up being a mistake, however, if you are not careful. While conventional planning opportunities can help assist with tax problems, they might not go far enough to address family dynamics that will long outlast your savings and you.

This is why it is important to have an estate planning attorney who is knowledgeable about possible issues of family conflict and one who can help you avoid these challenges and to successfully navigate a plan that looks into the best interests of you as well as your individual family members. The support of a lawyer is instrumental in outlining what is in your best interests and how to minimize the potential for conflicts and legal issues down the line.

Retirement Gender Gaps

A new Merrill Lynch study has found that women have to work harder than men. This is especially problematic given that longevity numbers for women indicate that they are likely to live longer. A woman may outlive her spouse by 10 years or more, putting additional pressure on her if there are not sufficient financial assets to support her. Women have to start planning and saving for retirement earlier on and must also work longer in order to enjoy pension and Social Security benefits. plan for estate NJ

Women often have to play catch up and worry about the fact that they live longer. Both can present serious problems.

Pay and debt disparities are some of the common reasons women enter into the workplace with less opportunities than men to begin with. This means they must play catch up over the course of their life. Even combining finances with a spouse calls for additional planning opportunities as someone who may suddenly lose a spouse may be in the position of finding it difficult or impossible to move on with their life. This is particularly true if issues surrounding long term care emerge immediately.

If you want to talk about how to best save your assets and then plan for them in your retirement, set aside a time to talk to an experienced estate planning attorney today.

More Workers Are Concerned About Retirement Benefits Than Health Care Plans

Anyone who is looking forward to their future will be cognitive of how their retirement plan connects in with their overall financial goals and their estate planning. Retirement plans are often a significant asset and one that can draw in employees. retirement-estate-planning-NJ

A new study finds that employees in the United States marketplace are more focused on retirement benefits than on healthcare benefits and there is good reason to be mindful of this. With the average person in the United States living longer than ever before, it is important for both men and women to be aware of how their retirement benefits accumulated over the course of a lifetime can influence their ability to be stable when they do retire.

A survey of 5,000 United States employees recently released this week found that two-thirds of respondents were willing to have more money taken out of their paychecks every month to support more generous retirement benefits, and only 38% of those same respondents were willing to pay more each month for better health care benefits.

Although employees may feel vulnerable about their longtime financial prospects, you can take you future into your own hands by gathering a team of experienced professionals such as an estate planner, a financial planner, and retirement planning specialist to help you accomplish your goals.

Financial Matters You Must Consider in a Second Marriage

Day to day financial management, liabilities and assets are all of unique concern to people in second marriages or blended families. Whether you are remarrying after the death of a spouse or after a divorce, it is important to enter into this with new and smart financial planning.blended-families-estate-planning

There are many different things to consider, including how you will address your future financial wishes and your current financial situation. It helps to begin with a comprehensive review of your liabilities as well as your assets. These liabilities can include student loan debt, credit card balances, mortgages, car loans and more. Your assets can include a house, stocks, bank accounts, cars, insurance contracts and more.

The day to day financial obligations should also be addressed with a new spouse. How will the monthly bills get paid? Some couples choose to put everything in a joint account, whereas others choose to have separate checking account and split their expenses in that manner. No matter what you select, it’s important to engage with an estate planning lawyer and a financial advisor to help.

Avoid These Financial Advisor Mistakes

Selecting a financial advisor, much like choosing an estate planning attorney, is a very personalized process and one that must be done with extra special care. Identification that you have selected the wrong financial advisor could come with many problems. Poor communication, a generic approach that doesn’t take your unique concerns under consideration, and high fees are some of the most common complaints lodged against financial advisors. 

It’s much easier to avoid a mistake in the first place by selecting the right financial advisor, so there are three major things that you should never do when you are thinking about hiring someone to work with. The first is believing everything that an advisor says. Much like any other professional, it’s valuable to get insight from an advisor but you should not take everything they say as completely accurate.

Never enter an important relationship without a high level of trust. Another thing you should avoid doing is believing nothing that an advisor says. If you’ve already been disappointed by someone in the past, there’s no doubt that you’ll be hesitant about whether or not to believe what this current person is telling you. But disbelieving everything they say could be a mistake. Finally, don’t forget the difference between delegating to an advisor and doing some work of your own. Outside professional advice is extremely important in articulating a plan that addresses your individual needs, but it is equally important to ensure that you have done your homework on your end when your advisor gives you materials or suggestions.

Don’t Forget to Plan for Long Term Care

It seems like every day you may hear about updates to Medicaid and Medicare, and many people who have scheduled meetings with estate planning attorneys come in very confused about the difference between Medicaid and Medicare. Although both programs were created by federal laws, they accomplish very different things. 

If Medicare does not pay for long term care, you could find yourself very stressed out how to proceed and protect yourself. Most people are already aware of the benefits of long term care insurance, but fewer insurance companies are offering these traditional policies and it can be very expensive. Other products that cover needed services like continental care, home care, a nursing facility, recovery or an indemnity plan have come into the marketplace. Furthermore, there are some life insurance policies you can purchase that may pay for long term care and similar services if they are outside of traditional LTC setting.

You’ll also want to set up a time to consult with an experienced Medicaid planning attorney to discuss how to qualify for this critical government program in the right way and ensure that you are not facing any penalties for the way that you approach planning. A consultation with a Medicaid planning attorney and an estate planning lawyer can ensure that you have the assets set aside for your retirement that you may need, while also getting the peace of mind that you have taken the necessary steps to protect yourself in terms of needed long-term care.

Given that so many people will have to rely on some form of long term care services in the future, it is in your best interests to identify an attorney who can help you articulate a plan that protects your best interests.  

What Happens When Your Estate and Your Business Planning Combines?

As you are discussing things with your estate planning attorney, you may have already started or are considering starting a new business venture. You will have individual estate planning as well as business planning concerns that may have separate sections for estate planning and may be interconnected in some ways. There is no better time to protect your business than at the start of launching a company, but you can still benefit from business succession planning and estate planning if you have already been in business for some time. One of the most important things to protect is your trade name when you launch a company. business and estate planning

The name of a business is one of the issues that is resolved first in launching a new venture, but often, clients don’t give much thought on how to protect that name because they don’t realize that there is much to protect or are too busy with other issues. There is no better time, however, to protect your business’s name at the start of its use, simply because starting a new business doesn’t mean that your firm is automatically protected.

Additional effort is required and may involve other professionals such as an intellectual property attorney in addition to the estate planning professional you are currently working with. Scheduling a consultation directly with an attorney who can advise you about how your individual estate planning and your business succession planning may intersect, is important.   

What You Should Know About Retirement Rollovers in a New Job

Taking on a new position certainly means a big transition in your life, but it’s equally important to think about how this affects your retirement and your estate planning concerns. Financial advisors share that rolling over your existing 401(k) funds into a new employer’s plan is not always the most appropriate fit for all employees. Other options may include taking a lump sum payout, choosing an in-plan Roth conversion or opening a new IRA.retirement and estate planning NJ

Savers may choose to leave their money where it is, although some plan administrators say that your former position may impose restrictions. You will want talk to your financial adviser as well as your estate planning professional about how this influences your current life and your future. Rolling over into a new IRA preserves the most investing flexibility, according to financial advisors.

You will also need to make sure that all of your estate planning and beneficiary related materials are updated as well. When you move into a new plan, the materials inside your estate planning documents, such as your will, will be superseded by the beneficiary designation forms you have listed on your retirement accounts. This is what makes it so important to verify that these beneficiary designations are updated at least on an annual basis.

What Happens If You Inherit Property Overseas?

Many people wish to pass on valuable property, including that which may be located in other countries, to their loved ones. But what happens when you inherit property overseas. It might initially seem like a dream come true but it could come with challenges.

Many Americans who inherit property overseas will have to navigate a very complicated foreign legal system and often in another language. The amount of paperwork associated with these international receipts of materials in and of itself can be overwhelming. There are accounts that must be transferred, expenses that must be paid, and other issues that may arise based on the type of property you inherit. Furthermore, there may be a legacy associated with the property that you receive, making it difficult to hold up to these expectations if you were not anticipating the receipt of such property. When an American inherits property overseas, it falls under foreign statutes.

This means that wherever the real estate is located, the laws of that country govern it. This makes it all the more important to ensure that if you have access to foreign property that you plan to pass onto your loved ones, that you set aside time to talk to estate planning professionals in that local area about what this might look like for your family and how to best avoid challenges for them in the future.

Are There Significant Tax Consequences of Gifting After Death?

Your parents may have the best of intentions when passing along assets to you after they pass away, but the truth is that by making planning considerations during the course of their life time, they are actually setting their beneficiaries or children up for much better success. This is primarily because of what is known as the stepped-up basis. There is a major difference between gifted and inherited assets and how you choose to pass these on to your loved ones can make things much easier for them. 

If your loved ones choose to gift something to you over the course of their life time, you will have the benefit of paying same capital gains taxes that they would have if they were to sell those assets today. However, if they gifted to you upon death, you may be responsible for a range of different taxes and will have to pay a much higher amount due to these stepped-up basis.

The tax basis of any asset that is held until a person’s death is officially stepped up to fair market value, which means that setting aside time to speak with an experienced estate planning attorney can help you to avoid many of the most common problems and challenges surrounding the very process of passing things on to your loved ones.  

Make Sure to Include Collectibles and Art in Your Estate Plan

If you have valuable collectibles or art that should be a part of your estate plan, make sure these are not accidentally left out. Unfortunately, many people don’t even realize the true value of the art they hold inside their estate. A recent study identified in 2017 that more than 80% of collectors did indeed view their art collections as a form of investment but unfortunately, even these high net worth collectors may not appropriately plan for the distribution of these very valuable assets. include art in your estate plan

Thinking well in advance about how you may accomplish particular estate planning goals must incorporate your unique collections. You may assume that your collection has greater sentimental value, but it might also have a financial value that could cause in-fighting among family members or other challenges, should you exclude it from your estate plan or leave confusing or unclear plans. The IRS classifies collectibles as rugs, works of art, antiques, any gems or metal with some exceptions, stamps or coins, alcoholic beverages with a high value or any other personal property that is tangible that the IRS may view as collectible.

There are two primary ways you may be able to distribute your collectible property; donating them to a charitable organization or leaving the assets to your heirs. In either case, you’ll want to ensure that you have the estate planning materials and strategies in place well in advance.

Study Shows That More Nursing Homes Residents Are Sicker

A new Kaiser study confirms what many people already working in the long-term care industry already know; that there are fewer long-term care residents in nursing homes but many of these patients have decreasingly successful conditions. Investigators recently determined that approximately half of the people in nursing homes across the country had a diagnosis of dementia, whereas under one-third had psychiatric conditions such as mood disorders and schizophrenia. 

Approximately two out of three residents are currently taking psychoactive medications such as sedatives, anti-depressants, anti-psychotics or anti-anxiety drugs. The total nursing hours increased to more than four per resident day in 2016 and Medicaid is the primary payer for most of these facilities.

If you are thinking about looking ahead into the future and encompassing a comprehensive plan for your estate as well as your assets and Medicaid, you will need the experience of a knowledgeable estate planning lawyer.

Life Combination Policies May Fill Long Term Care Gap

Long term care insurance is known as one of the most expensive forms of insurance out there and it is extremely important for people to have long term care insurance coverage. Long term care insurance coverage provides a critical stop gap in the event that someone becomes suddenly disabled or affected by a cognitive or physical issue that renders them in need of nursing home care. New life combination policies have emerged to step in where traditional long-term care insurance falters. 

Traditional sales of long term care insurance policies have dropped by 60% since 2012. A newer option for ensuring against the risks of long term care costs includes universal life insurance that has long term care protection. In 2012, only 86,000 of these policies were sold, but that number surged to 256,000 in 2016.

Nearly half of retirees have indicated that they are not confident they will be able to pay for their own long-term care, according to research gathered and presented by the Employee Benefit Research Institute, and even higher portion of workers share that same concern.

And a 2016 study conducted by LIMRA found that the number of retirees concerned about long term care expenses has increased from 2006 numbers by 13%. If you are curious about how to thoroughly protect yourself against the cost of long term care and ensure that you have made the move to get help quickly and easy one, contact an experienced estate planner today.

Planning and Organizing Will Be Key for Estate Planning

Estate planning involves going one step beyond simply talking about the issues or thinking about how you might want your estate to be handled in the future. Planning and organization are the cornerstones of a successful estate plan and it’s very valuable to sit down with an outside party who can help to ensure that your plans accurately reflect what you intend. 

Many people have a common goal of wanting to make their estate as easily managed as possible because they don’t want their children and other loved ones to have any difficulties after they pass away. Therefore, wrapping up affairs with as few problems or conflicts is a common goal for most people.

The first thing to do is to have a plan and to have clear storage locations designated for each of these materials. Hiring an attorney may seem overwhelming or like it can be easily skipped, however, there are far too many pitfalls in the process of estate planning that could cause you numerous problems and leave your loved ones paying the price in the form of a disorganized estate. It’s much better to sit down and walk through one document at a time to verify that your documents reflect what you actually intend that they will be viewed as valid by the state.

Six Ways to Afford Long Term Care

Long term care insurance is not the only way to afford your future, but it is one of six ways that you may be able to approach health care costs that may surge into your later years. Given that the average cost for a person turning 65, in need of long term care services, is $138,000, it is thoroughly responsible to ensure that you have a plan in place. 

If you have already checked whether or not a long term care insurance policy is possible or accessible and identified that it is not within your financial reach, there are still five other options you can consider to fund your long term care expenses. These include health savings accounts, adding riders to your current life insurance policies, using your personal savings, taking advantage of veteran benefits when you are eligible, and exhausting all of these options to have your long term care cost paid through Medicaid.

Medicaid planning requires advanced consideration and will likely need insight from an experienced estate planning lawyer who is thoroughly knowledgeable about how to protect your best interests. Scheduling a consultation today with an asset protection planning attorney and an estate planning attorney can help to clarify what’s next.

Best Side Hustles for Working in Retirement

Entering your retirement years doesn’t mean that you have to stop working entirely. In fact, for a growing portion of the retirement market, retirement is an opportunity to take on new and exciting side hustles. Having a side gig that helps to supplement your retirement income and gives you something to look forward to is extremely beneficial. 

Businessman Brainstorming About Retirement Planning

Women also face advanced challenges with retirement because it is likely that they have not set aside enough to help support their own retirement. This is why side hustles can assist.

Many of the different types of side hustles that can be beneficial for someone in their older years include those that allow them to be on their feet for a short period of time, such as dog walking. Others may benefit from working in the freelance marketplace because they are eligible to set their own hours.

Working in a part-time position on a side gig, such as building a website or writing a book can also help to bring in extra income while giving your mind something to focus on and feeling as though you have transitioned into a new phase in your life.

Plan for the Best… and Worst

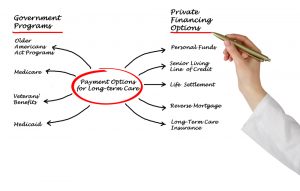
Don’t put off the process of estate planning, such as articulating important agreements like a power of attorney or your will because you assume that the worst will not happen to you. Payment Options for Long-term care

This is a catastrophic mistake that could end up causing problems for your loved ones down the road. It is far better to schedule a consultation with an experienced estate planning attorney today to ensure that your primary needs and concerns have been addressed.

The support of a dedicated attorney is extremely valuable when you find yourself in this situation. Looking ahead to the future means thinking about unanticipated events. A sudden disability or diagnosis of a medical condition tied to a car accident, for example, could represent significant changes in your life and you need to be prepared for how to address these. Having an estate plan or business succession plan, already stipulated in these cases, can make it much easier to adjust in the heat of a moment when you must be able to respond effectively and appropriately.

The support of an experienced attorney is highly valuable when thinking about how your estate plan will translate into individual actions. Schedule a consultation with an experienced estate planning lawyer today.

You can make things easier for your family members and your own peace of mind by setting up a plan you can count on in the event of a worst-case scenario.

High Net Worth Clients Must Have Experienced Estate Planners

Anyone who has an extremely high net worth must be mindful of the many different ways that their assets and their overall estate can be affected by taxes and retirement planning. 

High net worth clients often come with complicated needs, making it all the more important to retain the services of an experienced asset protection planning and estate planning lawyer. Many of these needs include succession planning for business owners, behavioral consulting, estate planning, tax mitigation, and asset protection planning.

The services must often extend into the help of other professionals, including investment management. Any advisors that are not offering specialized services must be mindful of the fact that it may be challenging for them to retain high net worth clients. High net worth clients want to know that they have an advisor they can turn to over the duration of their relationship and get questions answered as their cases become more complex and as their needs shift over the course of life.

An estate plan that must be updated regularly is even more important for a person with high net worth as they may be continuing to grow that worth and have unique considerations that evolve over the course of time.  

How Making Better Financial Decisions Can Help You in the Future

Many people are confused about investment basics and this can cause problems when they approach financial or estate planning. Financial planning unfortunately, usually isn’t taught in schools and investing or financial management are not necessarily intuitive, but it is critical to know how to plan for your own financial wellbeing. Many people believe that they should be doing all of these various things related to their investment and retirement planning and often become overwhelmed by so much information. estate planning in NJ about more than money

Learning about the basic types of investments and determining what you would like to achieve in your retirement, is a great way to begin with your end goal and then reflect backwards about the steps that you could take to protect your best interests.

Scheduling a consultation with a knowledgeable financial advisor and an experienced estate planning attorney can help you to understand all of the various assets that make up your current estate and how these should be considered together when you approach the future. The support of an estate planning attorney in particular, is very valuable because many people underestimate the volume of the assets inside their individual estate.

If you fail to include all of the necessary assets, you could expose yourself to unnecessary tax consequences and problems for your loved ones in terms of the state making decisions on your behalf because you chose not to engage in estate planning.