Should You Create an Irrevocable Trust for Your Spouse?

Trusts are a popular estate planning strategy because they accomplish multiple goals at once, including privacy, greater layers of control and allowing for support to the beneficiaries that you choose. When it comes to thinking about your taxable estate, you may be able to move some assets inside a trust for proper management, thus giving up control.
Creating an irrevocable trust now could help you to take advantage of today’s high exemption levels. Staying under the exemption amount means that you get money out of an estate now without any gift tax consequences and you can still enable access to the funds through a spouse with the remainder of the funds going to other heirs. These are called spousal lifetime access trusts or SLATs.

These are irrevocable trusts that have a spouse as a beneficiary and even grandchildren or children as remainder beneficiaries. Your spouse is eligible to tap into the assets inside the trust for education, health or general living expenses which can also benefit you indirectly. While you can use a separate SLAT created by your spouse naming you as the beneficiary, be careful about this being identical as this will raise questions with the IRS. For more information about this process, schedule a consultation with a lawyer.

Our estate planning law office can help you decide what kinds of strategies are most appropriate for your needs.
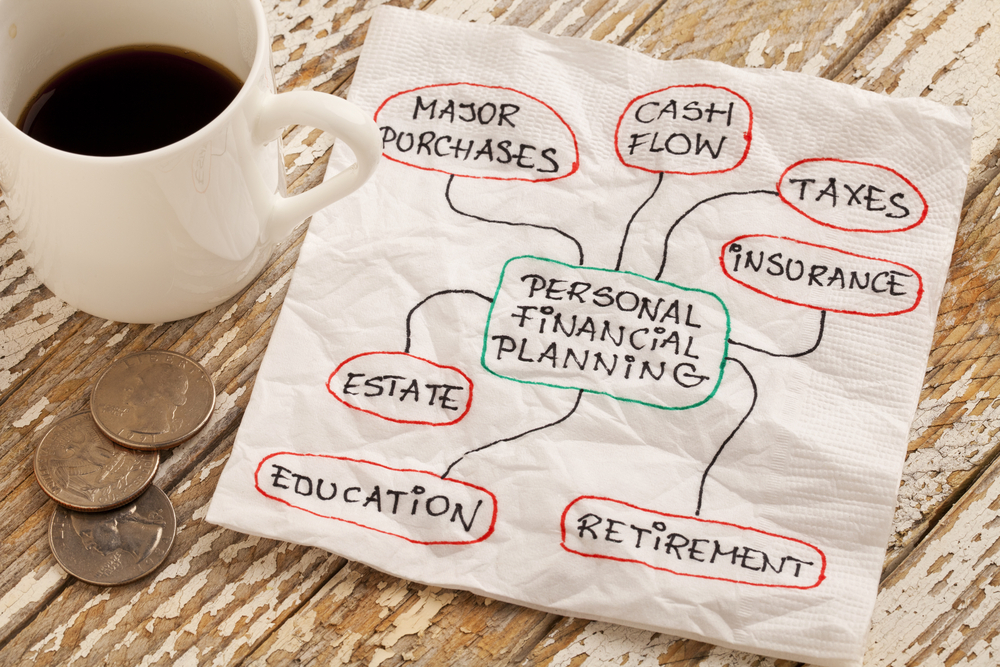
Is Now the Right Time to Use Your Lifetime Gift Exclusion?

If you currently own an asset that you anticipate is going to appreciate over the coming years, you may want to take advantage of exclusions that are available to you today.

The IRS has recently released guidance that indicates that you will not suffer a penalty for using up your gift exclusion exemption while you are still alive. If you pass away when an exemption is lower and had held on to an appreciated asset up to that time, the estate tax will be higher because a greater portion of the estate is taxable.

If you use up the exclusion, however, and Congress does not choose to move forward with lowering the lifetime exemption amount, you can still reap advantages from this for your loved ones because there will be less in your overall estate to be taxed when you pass away.

Remember, of course, that gifted assets do carry over a cost basis that goes to the person receiving the gift. You may be in a better position to hold on to the asset until you pass away so that your heirs can benefit from a step up in basis that it will receive in that time.

This also gives you a greater deal of security in case you were to need the money for an uncertain future, such as unexpected costs with long term care. Gifting appreciated assets is another strategy you may be able to leverage when it comes to gifting. It doesn’t sacrifice any economic security in the short term but remember that the person who receives this benefit must have the item for at least a year. Make sure you consult with your experienced estate planning lawyer to learn more about some of the strategies you can use for the purposes of protecting your estate.

What Is Portability as It Relates to My Estate?

The Tax Relief Unemployment Insurance Reauthorization and Job Creation Act was signed into law in December 2010. This made significant changes to federal estate taxes, generation skipping transfer taxes, and gift taxes.

This was the first time that the potability of an estate tax exemption was introduced. Portability is a concept that is only available to married couples. The amount of an estate tax exemption that is not used for a deceased spouse’s estate can be transferred to the surviving spouse in the event that the first spouse passes away and the value of their estate does not use up all of the exemption.

This then enables the surviving spouse to use the deceased spouse’s unused tax exemption in addition to their own exemption when the surviving spouse passes away. This is a federal level exemption and state level exemptions are only available in two locations, Hawaii and Maryland as of 2020.

The federal estate tax exemption is $11.58 million for those deaths that occurred in 2020. Exemptions are amounts that are subtracted from the total value of an estate and only the balance that remains after this is applied is subject to the estate tax.

Because of the substantial size of this in the United States, it is very rare for many people to trigger the estate tax amount. For more information about this might apply to you and various estate planning strategies you can use, set up a time to meet with an estate planning attorney.

What is a Charitable Lead Trust?

There are many different kinds of trusts and you might use one or more to accomplish the goals in your estate plan. Because trusts can be complicated and minor mistakes can prove very problematic in the administration of the trust, you should use the support of an estate planning attorney to create yours.

You can create tax savings without giving up the assets that you want your family to receive some day by using a charitable lead trust and a cause you care about. A charitable lead annuity trust pays a certain amount to the philanthropic organization or foundation of your choice and is most attractive when interest rates are low. A charitable lead unitrust, on the other hand, pays a variable amount each year based on the total valuation of the assets inside the trust.

With a unitrust, if the assets inside the trust increase in value, the payments made to your chosen organization go up too. You can fund your donation in a charitable lead trust using real estate, appreciated securities, closely held stock or cash. You’ll want to consult with your legal and financial advisor before deciding to move forward with a charitable lead trust. It is very important that all of the details are carefully evaluated and structured to leverage maximum achievement of your goals.

Can I Reduce My Estate Taxes by Paying for Education Now?

If you are looking ahead to your future estate taxes and looking for a strategy to minimize them, a consultation with an estate planning lawyer can help you to address many of the most common issues and concerns that come up in connection to this.

Savvy planning can make things easier for your loved ones in the short term but also can benefit you in the long term. Paying tuition or medical bills doesn’t count towards your annual exclusion or the estate tax exemption so long as the checks are written directly to the school or health care provider. This can help to reduce the size of your taxable estate and can help provide a valuable gift to your loved ones who may need the money for their education or their expenses.

Many people are currently reevaluating their charitable contributions and gifting to grandchildren to determine if the strategies they had in place prior to the pandemic are sustainable. If you make any short term changes that reduce your gifting strategy, you’ll still want to have a plan for revisiting these in future times to ensure that they align with what you intend to accomplish with your family.

During these uncertain times when there are many possible changes with estate laws in the works and a great deal of unknowns as it relates to the pandemic, it’s important to have relationships with trusted professionals like estate planning lawyers to allow yourself to make informed decisions as needed.

Have You Planned for Your Invisible Estate?

Many people often make the mistake of assuming that their will controls the distribution of their full estate. It’s easy to forget that certain aspects are automatically excluded under the terms of your will.

There are three common methods by which assets might be transferred to your beneficiaries after your death outside of what’s named in your will or what goes through the probate process in your state. These include beneficiary designations, a will or a trust or joint ownership with right of survivorship.

Beneficiary designations are common with IRAs, 401(k) plans, pensions and life insurance. The accounts are distributed directly to the beneficiary that you name on the form when you pass away and your will does not have any say over these benefits. If you own property as tenants in common with another person, your 50% of the property will follow the provisions in your will.

However, jointly owned property with right of survivorship generally goes to the surviving joint owner regardless of what is stated in the will. If you have questions about this process or how to leverage your own individual estate planning, schedule a consultation with an experienced and knowledgeable lawyer in your area today.

How Much Tax Could Someone Above the Estate Tax Threshold Pay?

When you pass away, your estate could be taxed above certain thresholds established on an annual basis. This has risen to $11.7 million in 2021 with an exemption that is set to expire at the end of 2025.

However, it is possible that legislative and fiscal pressures could push a change to occur sooner rather than later. This large exemption means that many people have put off the process of estate planning altogether but this could be a significant mistake.

The federal estate tax and gift tax is currently 40% on those amounts over the $11.58 million threshold in 2020. This is outside of the fact that some individual states can also levy their own estate tax. If the gift exemption is decreased by a lot by any oncoming legislation, this will make it very challenging for people with higher amounts of assets to minimize their taxable estates.

This is why it’s important to have an established relationship with an estate planning lawyer to help keep you aware of these issues and help you to navigate these circumstances when they occur.

Our estate planning law office can help support you as you move forward with your planning process.


New Study Shows That Employees and Workers in America Are Stressed About Their Financial Future

A recent study completed by Greenwalt Research and the Employee Benefit Research Institute determined that employees are facing significant anxiety and stress when it comes to their financial futures.

Over 1,000 workers in the United States between the ages of 21 and 64 were interviewed for this study. 2 out of 3 employees cited concerns about being worried about their household’s financial wellbeing and their own financial futures. Employees also stated that efforts in the workplace are critical to their physical as well as financial wellbeing.

Just over one third of employees who participated in the study said that their employer offers a financial wellness program, which did indicate an increase from previous studies. However, when it came to furloughed workers, the outlook was less positive. Fewer than 1 in 4 furloughed workers said that their employer’s efforts were very good or excellent when it came to improving their financial or emotional wellbeing. The survey specifically dove into topics, such as traditional defined benefit plans, retirement savings and health insurance and how this affects workers in terms of financial security.

Now is a good time to consider the benefits of comprehensive estate planning and financial planning to update your documents and strategies to adapt to changes in your life and in the world at large. The pandemic has prompted many people to think about how to best protect themselves and their future, so you’re not alone if you’re ready to discuss your options.

If you are curious about planning for your own financial future or have questions about the process, schedule a consultation with an experienced estate planning lawyer to protect your interests.


Three Things to Care About Within Your Estate Plan

You want to keep administration and tax costs as low as possible but there are other items that should be important to you as part of your estate plan. These include yourself, your family and your philanthropic interests.

You might assume that your estate planning actually doesn’t have anything to do with you except that it’s your responsibility to verify that the assets you wish to pass on to beneficiaries can properly do so in your documents but this is a common error.

As your assets increase and as you grow older you face unique estate planning and asset protection planning concerns that should always be discussed directly with an attorney. Planning for the future needs of others can help you maximize lifetime advantages as well. The most common reason for carrying out your estate planning is to protect your family.

Your spouse should decide how the assets will be administered for the maximum advantage of the survivor if you are married. Your spouse will face heavy and new burdens when you pass away but if you have children, grandchildren, nieces, nephews or other family members, you’ll want to make sure that you have taken extra care to include them in your estate plan.

The final aspect of covering what’s most important to you in your estate plan are your philanthropic interests. Don’t overlook causes that advance many different aspects of society. It is likely that there’s something personally connected to you that could be included as part of your estate plan and you’ll want your charitable goals to be in harmony with the needs of your family. Make sure you discuss how to make these important distinctions and still accomplish your planning goals with the help of a lawyer.

Does My Estate Plan Require Supplemental Care?

If a loved one has been diagnosed with a debilitating illness or dementia, there is a good chance that they will need care in a nursing home or the support of a skilled nurse in their own home at some point in the future. Turning to Medicaid to pay for these bills is often the first response of family members in crisis, attempting to help this loved one make such a transition.

A supplemental care trust may be a more appropriate option for leaving your estate to a family member who is expected to need government benefits, such as Medicaid, or who already receives these important programs as a result of special needs. Don’t let your good intention of leaving something behind for someone who needs it to have the unintended effect of causing them to lose this critical government support.

Also referred to as a supplemental needs trust, this tool enables the government benefits recipient to continue getting those services whereas the supplemental care trust can be used to pay for services such as entertainment, internet service, therapies, care manager services, clothing and travel, in addition to goods. Make sure that you have a qualified attorney create your supplemental needs trust for you to ensure that it complies with relevant rules and laws. 

What does a future long term care plan look like? If you’re not sure how to answer this question or even figure out what the first few steps are, it’s helpful to speak with a lawyer about what to expect and how to proceed. The support of an attorney can be instrumental in laying out your plan for you.

What to Know About Estate Planning When There’s an Addict in Your Family

Having an addict in your family can be a very difficult situation and this can prompt numerous concerns around the process of estate planning and naming someone as a beneficiary who might not be in a good position to receive or use funds. Creating a written revocable living trust, naming the person in question as a beneficiary can be one way to accomplish your estate planning goals and still protect that person.

You can require, for example, that the trustee make any necessity related payments directly to the provider rather than cash being given to the beneficiary. For example, this might include a mortgage company or a landlord or a health insurance company. You can set aside specific standards for the trustee of the account regarding disbursements.

Some of the most common categories that you can authorize for the trustee include maintenance, education, health and support. This leaves enough room for the trustee to make some discretion but can also require some certain level of standard of living or other needs.

Include a provision that will name the entity or person who will be eligible to receive any funds remaining in the trust if the family member in question were to pass away. These are complicated and important issues to consider from an estate planning perspective. These should always be discussed with a trusted and knowledgeable estate planning lawyer.       

Can You Remove an Executor?

An executor is appointed to close out the affairs of a deceased person. The last will and testament is used to name the executor, but if one has not been named or no will exists, the court needs to appoint a person in this role.

An executor has what is known as a fiduciary duty. This means they must uphold the interests of the estate and the associated beneficiaries above their own interest. A violation of this could lead to the removal of the executor. Anyone appointed in this position should know that they have this legal obligation and be fully prepared for what it means to have this responsibility and duty to the estate.

If you are an interested party to an estate and believe that the current executor has violated the law or the ethical rules surrounding this role, you might be able to ask the court to remove them from this position. This is a serious matter and claim and one that should not be undertaken lightly.

If you suspect that a fiduciary duty has been breached, it’s best to try to make sure this isn’t a misunderstanding first. In order to ask that the executor be removed, the person must be an interested party to petition the court and ask the judge to remove that person.

You must be able to show a valid reason for why you’re making this request, such as misconduct or incompetence. Simply because you are frustrated with actions the executor took legally does not mean you have met the legal grounds to pursue a claim to get them removed. You might want to meet with a probate lawyer to discuss whether or not any violations occurred. All beneficiaries have to be notified when a petition is entered to have an executor removed and the court will review the claims to determine the course of action.

Should You Convert Retirement Accounts for Tax Planning Purposes?

Do you have a goal of keeping current family money in the family when you pass away? There are several different steps to accomplish in this, each of which can be discussed with an estate planning attorney. 

A person who has a current 401(k) or IRA account could accidentally leave behind not just the assets inside the account but a significant tax bill. There’s an income tax liability, for example, that comes with children inheriting that IRA.

This is because regular income tax has to be paid on distributions from all traditional retirement accounts in the United States. In the past, your heirs had the opportunity to stretch distributions received from this fund over the course of several years to reduce their overall tax burden.

However, the account now must be liquidated within ten years after the death of the primary owner of the account. You might need to think about whether or not converting traditional accounts to Roth accounts, which have tax free distributions, makes the most sense for your family.

For more information about this and to decide what other assets need to be involved in your comprehensive estate plan, it is best to sit down with an estate planning attorney and to create a comprehensive inventory of all of the assets and debt associated with your name. This can help you begin to answer some of the most important and difficult questions around the estate planning process.      

What Happens If Your College Age Child Gets Sick?

This is a question you might not have contemplated until the pandemic raised concerns about health all over the United States. It’s come front and center for those parents who have a child who has either gone off to college for the first time or returned to campus for the first time since the pandemic started. No matter which of these applies to you, have you done estate palnning with this adult child before they left?

Given that it’s unknown what campus life next semester will be like, it’s a good idea to do everything you can to plan ahead and prepare. Getting the call that the school has a big spread of COVID or that your child is sick and needs to return home are real possibilities for parents in the next year, and estate planning can help to answer some very important questions during this time of uncertainty.

If you have a college age child, it may be important to create estate planning documents specifically for this purpose. If your child is away at college, you do not necessarily have the authority to make medical decisions on their behalf unless you have been specifically granted this legal authority in a power of attorney document.

A durable power of attorney document can be used when signed by your adult child stating that you are able to make care decisions on their behalf if they become incapacitated as a result of covid or any other medical condition. Without these documents you do not have the authority to act even if your child just turned age 18 yesterday.

During this period of transition when your newly legal adult might still have strong ties to home and rely on you for support in these important decisions, it’s critical to think about how these documents could help you avoid difficult situations.       


Do You Know These Three Trust Parties?

The establishment of a trust is usually a more advanced form of an estate plan and it requires at least three parties, some of who may be served by the same person. The first party to a trust is the person who creates it known as the creator, settlor or grantor. The second party to the agreement is the trustee. This is a person who has legal title to the property and the trust and manages the property according to the terms inside the trust agreement as well as applicable state laws.

In many cases, when the title to the property must be recorded, it is listed as in the trustee’s name not as an individual person but rather as the person trustee of the X family trust. The third party to a trust document and strategy is the beneficiary. This is the person who benefits from the trust and multiple beneficiaries can be on a trust at the same time.

There can also be different beneficiaries over time. Sometimes an individual might be known as an income beneficiary, meaning that they earn interest and dividends in income on the trust. Other beneficiaries can be remainder beneficiaries, which means they will get what is inside the trust after previous beneficiaries pass away or those rights expire.   

Creating a trust can be a key aspect of your estate planning, but it only makes sense when you have worked directly with an estate planning lawyer to select the right kind of trust. Given that you can accomplish many different goals with a trust, you want to choose the right one and fund it properly to get all the benefits.

What Makes Elder Law Distinct from Estate Planning?

What happens to your assets as you get older is of chief concern not just for estate planning purposes but also for your own elder law planning. The key differentiating point between estate planning and elder law is that elder law professionals look at the holistic process and consider how your key documents and assets can be used to support you throughout your life as well as your chosen beneficiaries after you pass away.

An elder law attorney will sit down with you to look at all of your unique circumstances and can assist you with the creation of estate planning documents, such as trusts or wills, but can also help you answer key questions around what your needs might be with regard to medical costs or long term care needs down the road. Experts in elder law will be familiar with many different concerns associated with aging and will have worked with many other clients in similar situations to help you avoid common blind spots.

A consultation with an elder law attorney can be extremely beneficial if you do not yet have an estate plan and have questions around what your estate plan should include. Given that many Americans are living longer than anticipated, you need to have more than a retirement plan to guide you into older years. Set aside time to speak with an elder law attorney about your distinct needs and how you can accomplish your goals.

Merging Two Families? Don’t Forget Your Finances

Becoming a blended family presents unique opportunities and some challenges with regard to your financial and estate planning. In 40% of all new marriages in the United States, at least one of the spouses was previously married. There are unique financial and estate planning dynamics that can come from merging families, especially as it relates to financial values, existing documents, money philosophies and even your spending habits.

There’s a good chance that the way you talk to your individual children about finances is different too. From savings plans to allowances, it’s important for you and your new spouse to get on the same page. In these circumstances, it’s a good idea to look at existing documents that both of you are bringing into the marriage.

Estate planning must be tackled together with your new family in order to ensure that your estate planning documents and strategies accomplish your goals. Once you’re married, your blended family should quickly reevaluate existing estate planning processes.

It’s important to think about how you will care for your children from your previous marriage and ensure that they are not accidentally excluded from your estate planning that you update across the board to reflect your new family arrangements. In addition to making sure that your new spouse is taken care of, you’ll want to talk with an estate planning lawyer to verify whether or not your existing estate planning documents protect your children from a previous marriage the way that you intended.

For further information about this process, schedule a time to talk with a dedicated estate planning lawyer.

Since blended families have so much to think about, you need dedicated advocates in your corner to help you.

A Plan for an Intentional Retirement

Those approaching retirement today and looking forward to it in the next couple of years have likely navigated their entire life with a sense of purpose, and exiting the work market full time doesn’t mean you give up this purpose. A recent survey of retirees found that 55% of them said that retirement was viewed by them as a new chapter in their life.

That same study identified that over 95% of retirees felt that it was important to continue growing and learning at every age. In order to accomplish retirement goals and continue driving forward with a sense of purpose you need to be financially prepared.

Asking yourself some of the tough questions and engaging the right team of professionals can help you navigate this new process. This includes asking yourself questions, such as:

  • Will I still be able to retire at the age that I intended to?
  • How will retiring at different ages impact my Social Security benefits?
  • Will I need to prioritize some of my goals because I don’t have the security that I anticipated as I get closer to retirement?
  • How will I incorporate estate planning intentions into my existing financial strategy and retirement options?
  • What role, if any, does philanthropy and charity play in my overall financial strategy?

It can be very rewarding to approach and live through your retirement purposefully but it is hard to do it alone. Having the support of a dedicated team of estate planning professionals and financial experts can help provide important questions and insight as you navigate this process.

Our NJ estate planning law office is here to help you no matter what questions you have on the process.


Advanced Estate Plan Strategies Aligned with Low Interest Rates

The current environment of your state and the federal economy and relevant laws can help you to determine whether or not your estate plan meets your goals or needs to be adapted. The Federal Reserve’s decision to keep interest rates very low has made a good environment for you to leverage advanced estate planning tools such as a grantor retained annuity trust or a charitable need annuity trust.

These are two techniques that allow for the transfer of wealth to occur at a reduced gift tax expense and provide that the future appreciation of any individual assets inside of them move on to the new beneficiary without exposure to the estate tax of the individual. A CLAT pays a fixed sum to a determined charity for a certain number of years after which point the remainder will pass to the creator of the trust’s family.

The GRAT pays a set sum back to the creator of the trust for a fixed number of years, then allowing the remainder to pass on to the family. Both of these advanced estate planning strategies can be most effective when you move an asset that has significant appreciation potential, such as a closely held business that you anticipate a successful sale of in the future. Given volatile capital markets currently and low interest rates, this is a good opportunity to evaluate these advanced strategies with your lawyer.


Checking Out of a Relationship or Home? Time for a Checkup!

In normal times and especially in a pandemic, many people use natural pause points to take stock of their lives and determine their next moves. For you, this might look like moving out of a home that was big enough to raise your kids in but too big to justify alone or with a spouse. It could include leaving a first or second marriage or trying to relocate to a new state where the conditions are more favorable to you financially.

No matter what moves you’re making in your life or you have on your horizon in the near future, it’s time for a checkup on your financial and estate plans. Your current plans might work for the conditions you’re in now, but making big changes means you need a step back to determine how your new life fits into the fold.

From thinking about your long term care plan to physically updating your will or beneficiary forms, there are a few tasks on this to-do list to consider when you’re “checking out” of your current conditions. It’s easy to miss some of these details, but they are important aspects of your life and plan. It’s best to partner with a dedicated estate planning lawyer to work through all the details and get the confidence that comes from having a comprehensive estate plan in place.

Are you concerned about how you move forward with your life in a way that protects your personal interests and your loved ones? You’re not alone. Estate planning lawyers in NJ can assist you with reviewing your current plan and making the necessary updates so that you have a future that’s bright for yourself and enables your loved ones to have an easier time moving your estate through the administration phase when it comes time to do that.