A Key Tip for Passing an IRA On to Children

Many retired individuals have access to both a tax-deferred account and a tax-free IRA. As a result, common advice from financial advisors includes suggestions for leaving the Roth behind to your children as it allows a tax-free withdrawal system over the course of their life. This is not always true, however. shutterstock_264759869

If you instead use the Roth for your own needs and set aside the traditional IRA for your children, they may ultimately get a bigger inheritance even after the income taxes on each withdrawal are factored in. The critical factor here is to compare your own tax rate with the tax rate of your beneficiary.

A child who has a lower tax rate than you do will be able to take a bigger inheritance if you leave them the traditional IRA. If the opposite is true, you may want to consider leaving the Roth instead. These calculations might be easy to accomplish when there is one heir to the retirement funds, but it becomes much more complicated when a parent has two or more children falling in different tax brackets. Make sure to set up an appointment with your financial advisor to determine how to best equalize the inheritances.

To learn more about passing on your retirement benefits and how to best accomplish this with estate planning, set up a meeting with our office today.

Benefits of Going from Sole Proprietor to LLC

If you are currently running a business set up as a sole proprietor, perhaps this structure served you in the past but it might be time to move on. Upleveling your structure can be beneficial from the perspective of protecting assets. It is not the right choice for everyone, though, so you should consult directly with your asset protecting attorney to determine the right move for you. shutterstock_192058409

A sole proprietorship converting to an LLC may help protect your individual assets from debts and judgments, but it could also carry potential tax benefits as well. Even if there are multiple individuals involved in the running of your company, creation of an LLC could help to tax profit distribution and have it taxed at an individual rate.

An LLC does not need to be a complicated structure, but it is often a logical next step for the business owner who has operated under sole proprietor status in the past. In addition to providing asset protection, it also signifies a sense of credibility regardless of what industry your company is in. If you want to learn more about the structures to consider when moving from a sole proprietorship, contact an asset protection attorney today. Your business is critical for your future, and your structure should reflect your growing needs.


Succession is a Critical Conversation for the Family Business


In the post-recession era, family businesses have become extremely important. Many disenfranchised workers took the opportunity to launch their own companies during this time, and now home businesses make up 50 percent of gross domestic product and nearly 60 percent of all jobs in the U.S.

Despite this rapid growth in the home business sector, many of the owners of such companies do not believe that their businesses will succeed beyond the current generation. Much of this has to do with generational differences, financial priorities, interests, or even familial disputes. In order to survive, even a home-based business has to have goals and objectives based on a collective vision. shutterstock_312773633

If you own a home-based or family business and would like to consider passing it on to the next generation, make sure you consider all decision-making processes in writing. If you plan to pass the company on, successors should be identified clearly and early on. Estate planning for you and for any concerns related to the business should be conducted by factoring in transfer scenarios and tax ramifications.

Contact us for more information about planning for business succession. Set up a meeting today by contacting info@lawesq.net.

Are Concerns About Private Medicare Founded?

Several of the country’s biggest health insurance companies are planning to merge, but this is raising concerns about a serious lack of competition in the Medicare marketplace. According to a new report, in fact, there is not enough competition anywhere in the country when it comes to Medicare. Research comes from the Commonwealth Fund, which found that up to 97 percent of markets in counties across the United States were “highly concentrated”, meaning that a handful of companies controlled the market. In rural locations, this concentration was even more pronounced, leaving little room for competition. shutterstock_288255239

Over the past few decades, insurance companies have encouraged private plans as alternatives to traditional Medicare options. Medicare provides coverage to about 66 percent of all beneficiaries. Some of the leading players in the private insurance market for Medicare are Humana, Aetna, and UnitedHealth Group. Those who support private insurance options believe that Medicare costs are reduced while the quality of care is boosted.

If you are concerned about healthcare costs associated with aging, you likely have questions about both Medicare and Medicaid. Long-term care costs funded with assistance from Medicaid can be a critical way to help a loved one receive the care and support he or she needs, but there are specific qualifications in order to receive the benefits. To learn more about qualifying for Medicaid, contact our offices to learn more.

Do I Really Need an Estate Lawyer?

With so many services and websites promoting do-it-yourself options these days, it’s tempting to think that you can handle the majority of your estate planning needs on your own. These services make it seem like a basic approach to managing your estate will completely protect you. There are two primary problems with this approach: it assumes that one size fits all (and this is rarely the case with individual situations or with state laws) and the margin for error is quite large. In fact, errors made in these “do it yourself” approaches could end up invalidating what you thought you were planning for. shutterstock_255529753

If you do not follow state laws with regard to your estate, your loved ones may be the one paying the price down the road. Even if you want to start with a base document to have a lawyer review it, this is essential so that you know that your document is valid and complies with any necessary laws.

A good estate planning attorney can help you with more than the basic documents you need for estate planning, too. Someone in this position can help you plan ahead for the future by thinking about ways to successfully pass on your assets with minimal tax consequences. Having clarity in your plan also gives you a better sense of how what you’re passing on influences your loved ones or any charities you are leaving money to.


Estate Planning Tips: Transfers to Make Today

It is expected that the IRS will shortly announce changes to the transfer of corporate shares, limited liability corporation interests, and limited partnership interests to family members. In 1990, rulings pronounced the elimination of discounting the valued of such transferred assets, but it looks like these benefits could be in jeopardy entirely. shutterstock_247781833

The courts have allowed these options to continue on the grounds that something transferred on the basis of market value would always carry less overall value than an asset being held outside the possibility of being purchased.

This September, however, the goal may be to eliminate any discounts at all. If this potentially impacts you, or you have had this on your to-do list for some time, it is now a good time to contact your estate planning specialist to determine if you should move forward with any such transfers. Getting expert advice about changing rules and regulations is always recommended when it comes to your asset protection planning or your estate planning. Contact us at info@lawesq.net.

Protecting Yourself From Lawsuits With Proper Planning


Although most people are aware of the litigious nature of society today, they often do not follow this up with the proper planning necessary to protect their assets. It is well worth your time to put structures in place to protect you from future litigation. Without any planning, you could be putting your assets in jeopardy.shutterstock_228287125

One of the most basic ways to approach this is to put together an LLC. Even if it is basic to start with, it helps to put a distinction between you and your business. Without official making this distinction, the courts might assume there is no clear boundary. This leaves your personal assets at risk.

Additionally, be savvy about insurance. Make sure that you have considered all possible areas in which you might be exposed. Business interruption service, liability, and property and casualty insurance policies should all be considered. Review these documents annually so that you are clear that they match your evolving needs.

Contact us at info@lawesq.net.

What to Do With Sudden Wealth

Suddenly having assets that you didn’t anticipate can be difficult to manage even when you’re excited about the new prosperity. A sudden influx of wealth presents its own set of problems that require a measured and deliberate response. shutterstock_234386854

Give yourself a little bit of time to adjust to the shock first. During this period, avoid making any major decisions. It might feel as though you have overwhelming possibilities in the short term, and it is a good idea to take some time to decompress before making any final determinations.

Make sure that you seek out passions and endeavors that are a joy, but you should also set up a consultation with an asset protection specialist in addition to your accountant or financial manager. You may want to consider setting up plans for your future beneficiaries or talk about how you could gift to charity. All of these are important options that should be considered with care.

Reach out to our offices today to set up a consultation to discuss how an influx of wealth impacts your present and your future.

Managing Conflict in the Family Business

The foundation of a healthy family business is in adopting and using standard policies and procedures that help to avoid the informal setting that many family companies might be tempted to default to. When business and ownership interests overlap with family relationships, conflict is naturally more likely to emerge. shutterstock_246742507

One of the keys to handling this successfully is to keep clarity: no family should be on the payroll for the company unless his or her role is clearly defined. No double standards should exist about the way that family members versus unrelated employees are treated. Just as family members should not be given preferential treatment, they should also not be abused simply because of their status as a relative, either. Communication throughout the company should remain consistent.

Ensure that the line between family and business is clear. Boundaries should be established in written format and should be reviewed regularly to make sure that everyone is on the same page. Learn more about family business succession planning tips by staying tuned to our blog.

The Future of Healthcare

Medicaid and Medicare are both closing in on their 50th anniversary. As this happens, more private insurers are involved than ever. In the past, no one would have anticipated that 30 percent of people in the Medicare program or 50 percent of the people in Medicaid would participate in these in this manner. shutterstock_171880706

In 1965, it was felt by the leaders at the time that a social insurance system would better serve America’s populace than a commercial insurance system. The current presidential administration is hopeful that the Affordable Care Act will become the accepted logical outcome of these historical predecessors, but it does not come as a surprise to many that the current structure of our healthcare system is an ongoing challenge.

Now that 99 percent of people in the Medicare program have the opportunity to supplement this coverage with Medicare Advantage, there is concern about funding coming from the state level. Some states have seen enrollment grow much more quickly than anticipated.

Medicare Advantage is not the only program that is raising questions, either. The cost of prescriptions and qualifying for Medicaid to assist with long-term care support are chief concerns for individuals preparing for the future. If you have questions about your finances or your estate planning as it relates to these programs, now is a good time to set up a meeting with your elder law attorney.

Living Longer is the New Paradigm of Estate Planning

It’s no surprise that people are living longer, partly due to advances in medical technology. What many people do not realize is how this translates over to their planning for retirement and end of life care. Funds that might have lasted through a typical retirement and lifespan in the past no longer provide the comprehensive services that might be required for long-term care. Old

In the last 60 years, life expectancy has increased by approximately ten years. Now, a 65 year old can be expected to live until 85. The biggest risk faced by this longer lifespan is in outliving your resources. This calls for retirement planning and estate planning to work together.

Stocks and bonds, in combination with retirement plans, are likely to form the cornerstone of your planning. Other vehicles, too, should be incorporated into the broader spectrum. This includes insurance and gifting, which can work together to cut down on long-term care costs or make qualification for Medicaid easier.

Discuss these options with your estate planning specialist while keeping in mind the potential impact of drawdown of assets from health-related issues, taxes, and inflation. The key to success in this arena has to do with flexibility and early discussion.

What to Learn About Family Foundations from Paul Newman

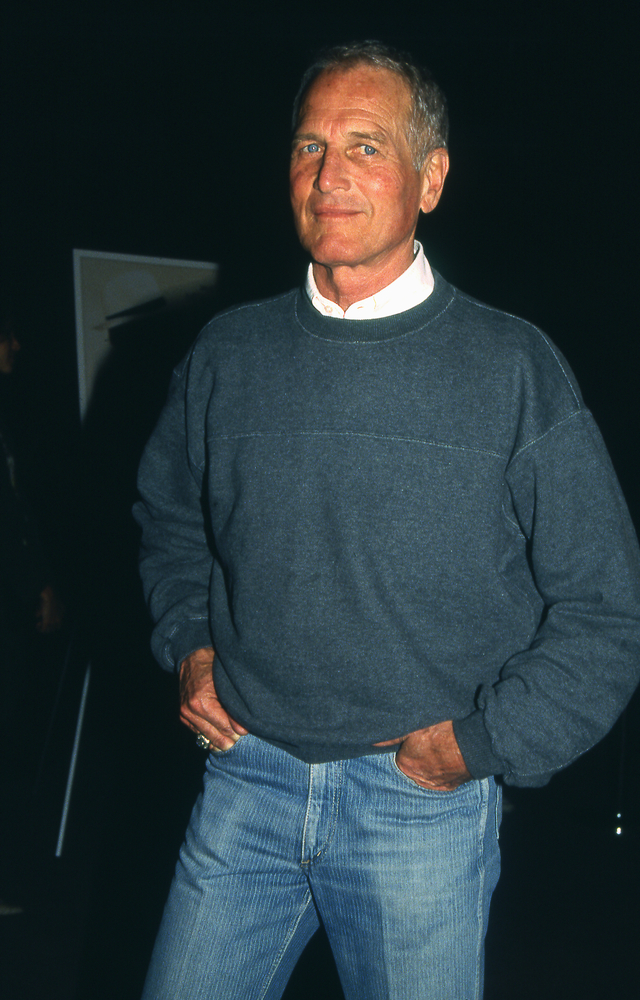
As is the case with many celebrity passings, there are lessons to be drawn from the estate of Paul Newman. In this particular case, it is important to understand that if a foundation will be run by family after the death of a loved one, early and clear communication is key. Rules for the governance of the foundation should also be outlined and explained sooner rather than later. The primary reason for this is because changes in estate planning can happen which alter the understanding of stakeholder roles in the foundation. shutterstock_261133046

Paul Newman changed his planning a dozen times before he died, shifting the plan from the original mandate that his four daughters would rotate through his Newman’s Own Foundation to omitting them entirely. With his four daughters removed from the picture, Newman shifted that responsibility to two of his long-time friends and collaborators.

What made such a big difference for his daughters was that his original plans were to provide each daughter with $500,000 (an amount that was later changed to $1 million) and an equal part share of 50% of his estate, with the other 50% going to Joanne Woodward.

In the end, all the funds went to Woodward to ensure her care, with any other distributions to happen after his death. With these personal changes in his estate planning, foundation management can be affected if other stakeholders are not included in the conversation. Be sure to approach your estate planning holistically.

Asset Protection Tips from O.J. and Lance Armstrong

Perhaps these two celebrities are not the most popular out there as far as role model status, but they do have some valuable lessons for asset protection planning. Asset protection is an essential goal that every person should have, regardless of whether their estate is in the 7 figures or not. Unfortunately, exposures to risk are something faced by everyone, even if the type and severity of those risks can vary.

shutterstock_125329607

Retirement accounts are a key focus for both of the above-mentioned individuals. Even though the tax deferral advantages of traditional IRAs and 401(k) plans are well documented, there are asset protection benefits to using these tools, too. In the event that you face a legal liability or personal bankruptcy, some retirement assets can stay out of the hands of creditors.

Right now, personal retirement assets housed in an employer-sponsored plan like a 401(k) are shielded from creditors. Even if a party leaves the position where this plan started, rolling it over to the new employer provides the same level of asset protection.

Of course, the specifics of how to protect your assets is something you should discuss with your estate planning and asset protection planning specialist. Making sure you get an appointment on the calendar could go a long way towards preventing attacks against your assets in the future. Contact us at info@lawesq.net.

How an Unexpected Departure Can Impact Business Succession Planning

There are lessons to be learned from the sudden death of David Roth, general director of the Kentucky Opera. Unfortunately, families and business around the country suffer when an unexpected departure raises many questions about the future of a company or entity. Although it can be frustrating to realize the challenges of handling this situation too late, such an event highlights the value of business succession planning in the present for any company. shutterstock_286436105

The first step in such a process is to recognize the loss and begin the communication process as early as possible. Stakeholders should be made aware of potential outcomes of the loss of a key member of the company. Stakeholders might include employees, shareholders, or even donors depending on the structure of the organization. All relevant individuals should know that operations will continue as usual in the interim. From here, the next discussion should be about plans for moving forward and what permanent leadership might look like.

If you’re struggling with starting the conversation on succession planning, we can help get you thinking about key issues and questions to consider.

Rights of the Elderly in Nursing Homes

Abuse and neglect of elderly individuals in nursing homes is an issue that has been drawing more attention recently as family members and other loved ones discover unfortunate situations. A clear understanding of elderly rights can help to address any concerns your family might be facing with regard to cost and quality of care for the elderly.  shutterstock_225427774

The 1987 Nursing Home Reform Act, along with specific state laws on these issues, help to set standards. These standards are supplemented by certifications and accreditations that can tell you more about a particular nursing home.

Among the basic patient rights, you should expect that your loved one has a right to property, receiving information about care, refusing care, and visitation. Nursing homes should also respect privacy and allow patients to be free from constraint (in both physical or mental terms). The starting point for a family beginning the research process is to look at the facility online and to visit it in person. Learning more about how a facility operates can ease some of your fears about your loved one living there.

Estate Planning Tips for Artists

A working artist has the potential to create hundreds of unique pieces over the course of a lifetime. Determining what you want your legacy to be and what you want to happen to your art can be a difficult question, but it is one that is better addressed sooner rather than later. shutterstock_262339691

One of the most important steps you can take in this process is to document and organize your collection as an artist. This helps to increase public appreciation of who you are and why you make the art that you do. Organizing it properly can also increase the interest that a collector has in your art.

Important questions to consider in this process are:

  • How have you signed your art? Consider that works that are signed and clearly linked to a particular creator have higher values, but they also connect that piece with your overall collection for estate planning purposes.
  • Have you created a master list of all the pieces you have created, ideally with a title, photo, and the year of creation? Doing so can make it easier for your heirs if you plan to pass the collection along, but it also can be important for collectors or potential museum interest in your work.
  • How have you stored your art? As a general rule of thumb, do not throw anything away as you organize your art.

Asset Protection Planning: Just How Needed Are Savings?

One of the most important questions that retirees are considering is whether it is necessary to access retirement savings or whether outside income can help pay for some living expenses. With people living longer, there are many genuine concerns about outliving your savings. This has prompted many individuals with retirement in sight to see just how realistic their current savings plans are for the long run.

4DICNdNhKDVpyb2FF2PcZgPp-XOWdQDfiG-J_V7EdWc

Retirement savings plans are certainly an important component of funding a modest retirement, but there is a delicate balance between planning ahead for other generations and making sure you have enough set aside for yourself. The use of trusts and identifying all accounts where a beneficiary must be named is one route to planning ahead, as well as considering whether life insurance policies could pay out during your life, too.

Make sure you set aside some time with your financial advisor to discuss your retirement planning and how that actually translates to what your retired life will look like. Understanding typical monthly expenses and how longevity may affect your plans can help you course correct or identify other options, if necessary.

www.drpo

How to Start the Discussion on Succession Planning

In order to plan ahead for the future and reduce the possibility of problems down the line, you need to think about what you want to happen to your business. The most difficult part of this process is planning the initial conversation and avoiding any excuses or reasons to put this off. Business Succession0915

When you set aside the time to talk with relevant family members or stakeholders, do not let anyone convince you that the conversation should be pushed off or dealt with later. Once you make the commitment to think about the future of the company, stick to it.

It’s essential, though, that you do have buy-in from the people at the top of the company. Your current leaders should already be assuming key roles within the company and that they participate in the process of identifying additional talent and building the structures for the company to exchange hands in the future.

Finally, be sure to hold yourself accountable. As the figurehead, the responsibilities should trickle down to your other employees, but you must be willing to show that this is your commitment instead of just saying that it is. Outlining your goals in an official statement or your company’s strategic documents helps keep you on track with this. Ready to get started but not sure how? Contact us: info@lawesq.net.

Fast Facts on Guardianship and Conservatorship

As you grow older or as your parents grow elder, the need to be proactive with your planning becomes all the more important. At the very minimum, this means providing a trusted individual with your power of attorney. A more comprehensive estate plan will, of course, have many more elements in place, but this is a good starting position. POA

Not having a power of attorney can present legal problems if someone does need assistance with making decision. If there are behavioral issues with an elderly individual, a conservatorship proceeding will happen, likely meaning that all relevant parties come with their own legal representation. This can be very expensive for everyone involved.

If the issues are medical as opposed to behavioral, without a power of attorney family members are looking at a guardianship proceeding. This involves situations in which a loved one or friend attempts to convince the court that a guardian is indeed necessary and that he or she is the best person for the job.
If you would like to plan ahead so that your family members are not facing this difficult task alone, contact an experienced elder law attorney for more information.

Tips for Planning With Bitcoin Assets

As of this writing, the IRS views bitcoins as property. The digital currency has gained enough traction that the IRS has started to pay attention. Now, owners of bitcoin are responsible for recognizing loss or gain and filling out taxes and W-2s where necessary as a result. Money

To include bitcoins in your planning, follow these steps:

  1. If the value has experienced any “step up” since you have acquired it, holding on to the bitcoins could help to cover tax consequences upon a sale. If the value has decline, an immediate sale might be the best approach for handling the loss.
  2. Discuss the existence of any bitcoin assets with your beneficiaries; without a conversation, some might not even realize it exists!
  3. Just as you have shared the existence information with your loved ones, you should also communicate how this can be accessed. Share those details with your executor. A power of attorney might be necessary to aid the executor with access, so look into that with your estate planning attorney.

As with all digital assets, it pays to be educated about how the asset is treated and what options you have for passing it along. Work with a law firm that understands the changing landscape of digital assets and currency so that you can feel confident in your planning.