Business Succession Planning: Challenges of Selling the Family Business

Selling a family business, whether it’s due to lack of succession options, estate issues or the need for liquidity can cause problems as a result of sudden liquid wealth.

Passing on the family business also carries with it needs worthy of great consideration and counsel from trusted advisors. Whether to travel, work or pursue hobbies or philanthropy, the business structure within the family operated will be gone if the business is passed on to someone else and this can be an emotional struggle.shutterstock_321333917
Planning for all life elements should be pursued as an integrated process with defined goals. Investment has to move from the business into diversified streams with clear communication with all family members as far as the consequences of the sale. An individual thinking about passing on the family business should also be aware of lifestyle creep which means increasing spending just because the funds are available to do so.
Tips for Those With Elderly Parents: How to Prevent Danger in the Home

Confusion and dementia are serious concerns for the elderly population in the United States. Both of these can contribute to compromising freedom and flexibility for an elderly individual, and prompting family members to be concerned about the appropriate level of care necessary for individuals in this situation.

The first key to handling dementia and confusion is to address any treatable problems that could be eliminated. These include sight, hearing and depression, for example. In balancing safety with independence for your elderly loved one, consult friends, caregivers and relatives for insight into likely behaviors and risks.shutterstock_170076899

Issues may include how long an individual can remain alone and whether your loved one can safely get back to his/her home when going outside. Another concern to be aware of is whether your loved one is capable of recognizing danger signs like smoke and appropriately calling for help.

If the senior you are concerned about already experiences life threatening episodes, you need to ensure that he/she has access to proper medications and proper dosages. Basic concerns like being able to prepare food and turning off the stove or oven and safely using the toilet and knowing who is appropriate to let inside the home are also key concerns when you are addressing issues like dementia and confusion. For more information about safely helping your elderly loved one, contact an elder law planning attorney today.

Estate Planning for the Never Married

According to PEW research, in 2012 the number of unmarried individuals aged 25 or polder had reached 20% of the population. This is a significant increase of 9% since 1960. Although the majority of individuals think that estate planning follows after marriage, if you’re not married the concern can actually be even greater.shutterstock_162693635

There is no clear path for decision makers and no plan means defaulting to an expensive and rigid legal state structure if you are not married and aim to avoid estate planning.

One key to avoiding these challenges is to reevaluate your plan every five years yourself as friendships and relationships may change relative to who possess the healthcare proxy, power of attorney and the like.

A second key is to consider carefully the advantages and pitfalls of combining financial and legal medical decisions in one single person. Contact an estate planning attorney to learn more about your options to determine what is most appropriate for you.

Lamar Odom and the Importance of a Living Will

The incident and attendant health crisis of Lamar Odom are a sobering teaching point. Life changes and disability or death can be sudden and they should be planned for. In the California legal system, this meant that legally, a marriage was intact. shutterstock_305675126

The absence of a healthcare proxy, living will or power of attorney placed the responsibility for medical decisions in the hands of the still current wife, a situation that most individuals in divorce would not wish. The Odom case demonstrates that the intersection of divorce and estate planning can be complicated and something you should contemplate ahead of time.

While divorce severs the majority of relationship responsibilities, an estate plan requires updating and careful consideration at the time so that caregiving wishes may be separated from divorcing parties. To learn more about how to structure your estate planning in line with your current needs, contact an estate planning attorney today.

Key Protection Tools for Guarding your Assets

One of the most basic steps to take in asset protection is using insurance. Insurance can help to protect your assets and an umbrella policy brings with an active defense of your assets through the insuring company.shutterstock_237576088

Your retirement accounts, however, are protected through ERISA and bankruptcy law and because these often have matching contributions from employer, maxing out on your own contributions is a great tool.

For the home and real property, the state of New Jersey allows persons to choose between New Jersey & Federal exemptions in the event of bankruptcy. Joint ownership through tenancy by the entirety can protect the home against creditor for closure.

An LLC may be another opportunity that is better than gifting assets as you retain control over those assets. The overall key of protection however, is consultation and planning that ultimately builds a wall around your assets, matching the height of that wall in terms of complexity in cost to the anticipated threats.

Business Succession: Twilight of the Boomers

As baby boomers age into their 60s and 70s, more of them are preparing to leave their businesses behind. In order to do this, baby boomers have to recognize that a lead time of at least 3-5 years is actually their best friend in the planning process. This allows you time to carefully consider all of your options and to put the steps in place to achieve success with passing on the business to someone else. Ownership succession in terms of selling outright frees the owner from future risk and locks in financial obligation of the buyer, providing cash to pursue future goals for the baby boomer.shutterstock_82215202

Management succession, which allows the individual to retain some level of ownership and risk, allows for transition into and through management a family and employees seeking the best positions moving forward. The key is that a long range planning option can help to maintain business value, improve employee confidence and cement a family legacy by providing financial opportunity for philanthropy.

Elder Law Preparation: A Legacy Account & Social Media

Planning for the future in terms of your estate may also include putting together a place for friends and family together and share memories. On Facebook, this can be done by memorializing an account. shutterstock_176941343

It is imperative that you give someone the access details to your account or set up a memorial option so that someone else can manage your page if you were to pass away. This can allow bereaving family members and friends to have a place to remember good memories about you and to be able to heal through the process of saying good bye. Shared content will remain and remembrances can be added, but such a memorialized account does not appear on birthday reminders or the ‘People You May Know’ feature of Facebook.

A legacy account can be created – person who can respond to a new friend request, post a final message – although this person does not have the capability to alter past posts, read messages sent to friends or delete friends. Look into memorializing your Facebook account today if you believe this is the right step for you.

What You Can Learn About Asset Protection Planning from the Ocean?


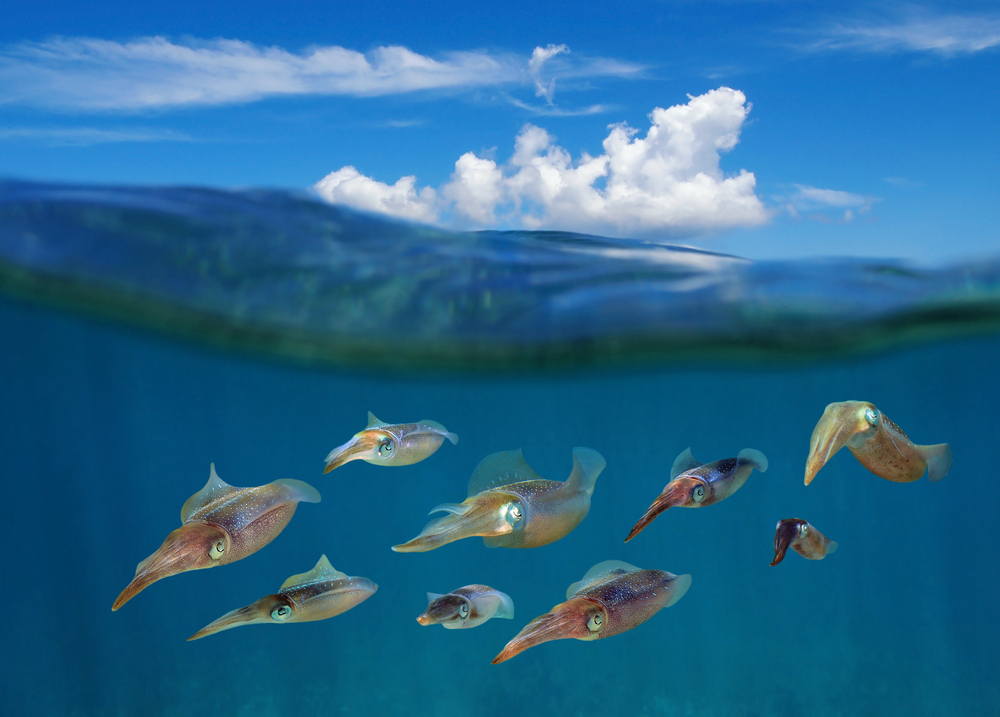
Much like offshore assets, the Caribbean reef squid is a master of disguise. Its skin composition allow it to blend into surroundings and in a sense to disappear. Assets should behave not as the tall reed in the ocean that attracts attention but instead rather be left to mature and grow sturdy.shutterstock_212413390

This should be your general approach with asset protection planning under the guidance of an experienced attorney. Misdirection and a sturdy structure can be found in LLC’s family foundations and trusts.

All of these can add a layer of protection making it more difficult for an outsider to understand who is who and who owns what, and thus leading some creditors to move on from trying to figure out the answers. Finally, placing assets not in cash but instead in collectibles or medals can make for allusive targets. Contact an asset protection planning attorney today if you would like to learn more.

Estate Planning is for Singles as Well


Although the needs of a single individual could be different, the importance of conducting planning in this situation is just as important. A will or a trust ensures that the state does not have to make determinations about a person’s property after he/she has passed away. This instead empowers a trust administrator to change or make decisions as needs require.shutterstock_60631654

If probate is necessary, required notification of all the impacted arrears can be costly and time consuming. If beneficiaries on the various accounts are not monitored or updates are not given, undesired persons can receive benefits to which they were not entitled. Finally, a power of attorney can be important tool for a single person. Whether it’s for healthcare or a regular power of attorney, this ensures that choices are made not by a court but instead by a trusted friend or colleague.

The Three Steps to Estate Planning

While techniques and strategies abound for estate planning, motivation to act in this manner is harder to trigger. Many people fear volatility and uncertainty leading them to become decisive. Many others are put off still by a perception that they do not need estate planning, meaning that they skip out on the process altogether.shutterstock_165450731

Solutions are much better understood when initiated with open ended questions. This should help illicit what a person’s ultimate wishes are and the tools they are currently using, followed by an evaluation of whether those tools are working. Rather than looking at charts or statistics, looking at real stories from people who have faced similar situations can help explain other options. Finally, the key is to implement a plan that sees a benefit for the individuals such as avoiding higher interest. Contact an estate planning attorney today to learn more about your options.

Medicaid: The Community Spouse and the MMMNA

When a Medicaid applicant has been approved and placed in a nursing facility, the community spouse’s income does not figure into determining eligibility for that nursing care.shutterstock_294531311

But it is still important to understand the minimum monthly maintenance needs allowance. This can work the family funds in the opposite direction as the Medicaid agency will look at the spouse’s income and compare it to housing costs.

If the Medicaid agency determines that this is insufficient, an applicant’s income will be taken to aid the spouse and the remainder minus a personal needs allowance each month will go to the facility. For more answers about important elder law questions that you may have as you or a loved one approach the need for nursing home care. Make sure to consult with an elder law attorney who has worked in this field for some time.

Why is Business Succession Planning an Ounce of Prevention?


A person given a one-third chance of survival in life is alerted to this fact. But in many cases a person whose business faces the same chances will prefer to deal with the matter later on down the road.shutterstock_320674358

The key in this situation is a balance between business Goals and family relationships as well as balancing emotion and logic.

In the process of conducting business succession planning you should identify the objective first. Is it to sell the business? Is it to give the business to someone? When will this take place? And who will be the key parties involved. After this initial need has been accomplished, it is time to consider the financial need. Does the retiree need business proceeds on which to live and if so, how much and how will these be paid out? And finally, key employees should be kept for the purposes of continuity and employment agreements can aid in this situation, building incentives and using non-compete agreements for structure.

What Happens to Your Debt When You Die?

Although there’s plenty of talk about how you should prepare your assets for your death, it’s also beneficial to think about handling your debts.

If you have a will, the assets in your estate will be handed over to the state for determining your next of kin. A living will gives you the opportunity to have a say in where your estate is headed, though.

Once you have passed away, your estate will owe your final debts. If you have assets in your estate to pay for these, an executor will be responsible for selling those assets and settling with creditors. In most cases, if your estate cannot cover these debts, then the debts will die when you do. This is not always the case, though.

The major exception to your dying debts is when a loved one serves as a guarantor or co-signer on one of your loans. This means that this individual assumes the debt if you are unable to pay for it.

Student loans with the federal government will die when you do, but private student loans can be particularly difficult to get rid of- if there’s a co-signer and no assets in your estate, the banks can come after the co-signer. If you do have assets in your estate, a private student loan can quickly eat through these. shutterstock_172836131

Planning ahead for your estate can give you a realistic expectation about what your heirs may actually receive after debts have been paid. Talk to an estate planning lawyer to learn more.


What is a Captive Insurance Company?

In the process of putting together a risk management plan, your attorney or other advisor might suggest using a captive insurance company for your business. Knowing what this is and how it can benefit you is a good place to start if you’re not familiar with this concept. shutterstock_159587510

A captive insurance company refers to a business formed by a business owner for the purpose of insuring affiliated and related business risks. The premiums received by the company are invested as opposed to lost and this is one of the biggest benefits of using a captive insurance company.

Captives also give the business an opportunity to insure against risks that would be uninsurable on the general market. These risks may be too expensive or unable to be covered at all with traditional insurance. This also provides access to the reinsurance market. The owner is more easily able to determine retention levels and structure a more flexible program in-house when using a captive insurance company.

Although there are plenty of benefits for using a captive insurance company, it must done properly if the business owner wants to maximize these advantages. Speak directly with an attorney to learn more about how these should be structured and managed in order to truly protect your risks and provide you with maximum benefits.

What is the CEO Succession Crisis?

It’s been said that the CEO succession process is broken in America. Although many situations call for a new generation of leaders to take the reins of a business, surprisingly few businesses have taken advantage of planning opportunities to do this.

shutterstock_229999303

According to research from Harvard Business Review, half of companies with more than $500 million have no clear CEO succession plan. And those that do have plans are unhappy with them. The Corporate Leadership Council asked nearly 300 large company HR reps to rate their happiness with a succession plan, and only one in every five was pleased.

Simply put, a CEO who has been in place for several years with no clear succession plan is a recipe for disaster. The future of the company is at stake when this happens, exposing everyone to potential risks. Do you have a plan in place for your business? If not, contact a business succession planning attorney today.

Three Basic Reasons for Physician Asset Protection Planning

The successful physician may find himself or herself suddenly catapulted into a whole new income bracket after years of education and training. With this new income bracket come some great opportunities, but also some risks. Read on to learn more about three of the biggest reasons why physicians should consider asset protection planning.shutterstock_262395656

High Risks

Any profession where there’s a reasonable concern that you could be sued is a high-risk profession, and medicine definitely falls under this category. Effective planning can minimize or eliminate the chances for a creditor to tap into your income, but you must plan early and revisit it annually to determine whether you’ve taken the right steps.

Legal Process

You need to consider how the legal process could impact your current and future income. Protect what you’ve built with solid legal strategies from an asset protection planning attorney.

It’s About More Than Money

Your high-value assets and personal property should also be factored in, and these are likely to grow as your income and wealth grows, too. Make sure they are protected.

Strategies for Shifting Income for Taxpayers

Wealthy taxpayers who have incomes above a certain threshold should be aware of some basic tips for shifting incomes and minimizing the hit of taxes. One popular technique for addressing this concern is to gift assets to cousins, grandchildren, or other relatives. This is known as the gift tax exclusion, but in order to get the most out of it, you need to know the limits and how it affects your estate.shutterstock_327831587

One other option is a family limited partnership. In this scenario, the money is moved to others more indirectly, but as a result of the relatives either performing routine tasks or an outright act of bequeathing the gift.

Of course, your individual strategy will depend on your unique needs, and you should consult with an experienced estate planning attorney to craft the right strategy for you. Contact our office to learn more about shifting income.

Is a Revocable Living Trust the Best Way to Provide Asset Protection?

Although a revocable living trust is one of the most commonly recommended by an attorney when you are crafting your will or taking other estate planning steps, you need to carefully consider the own circumstances of your estate to determine whether it’s truly the best fit for you.shutterstock_264000620

The primary purpose of a revocable living trust is to avoid the frustration and expense of probate after you pass away. While this is a worthy goal for your beneficiaries, you need to consider whether a revocable living trust goes far enough if one of your goals is to protect assets. Don’t let your loved ones find out too late that creditors can relatively easily access assets inside a revocable living trust.

Even though the trust is a legal entity, for legal purposes you are established as the owner of the trust assets allowing creditors’ potential access to these assets. If you set up a typical revocable living trust, you will name yourself as the trustee. This gives you complete control over the assets transferred into the trust so that you can take property in the trust, take it out, sell it or give it away without any restrictions. For legal and practical purposes, the property is still yours. Bear in mind though that having control over these assets also means that a creditor might be able to tap into it in the event of a lawsuit.

You may need to speak specifically with your asset protection planning attorney to shield assets from creditors. Planning for asset protection has become of increasing importance in recent years and finding a law firm that can help you do this is easier than ever. Make sure to ask questions about their experience in asset protection so that you feel confident about the role they are playing for you. Contact us at info@lawesq.net for more information.