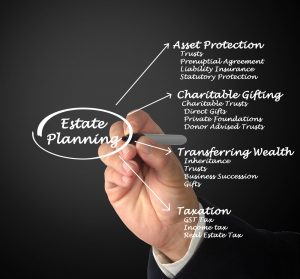
Protecting Your Assets Must Include a Basic Estate Plan

Although more people are recognizing the value of a simple estate plan, asset protection planning is also garnering popularity among people who are accumulating significant assets who wish to protect them. A NJ lawyer can help with asset protection planning
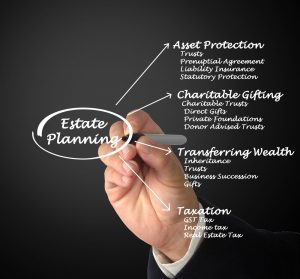
It may seem intimidating to put together an asset protection plan as the very name seems to indicate that you may have significant wealth to your name, but the worst thing you can do when it comes to asset protection planning and estate planning is nothing. If you become incapacitated or suddenly pass away without an estate plan, you make things much more complicated for your loved ones.

You could also lengthen the process for them to go through court to deal with your various assets and this could be catastrophic for your taxes as well. Being exposed to risks over the course of your life should prompt you to schedule a consultation with an asset protection planning attorney.

Without the appropriate legal documents and strategies in place, there’s no guarantee that the people that you want to handle your estate or your business will be able to do so. Family members frequently don’t know how a deceased person wants to distribute their assets and what he or she wanted in terms of funeral arrangements.

Asset protection planning goes one step further to consider the benefits of protecting your interests now while you’re still alive from creditors and other predators. Schedule a consultation with an asset protection planning attorney to learn more about how the process of estate planning can assist you with establishing assets well into the future.
Documents to Keep Indefinitely in Your Estate and Financial Planning Process


Although in the previous three blogs, we’ve discussed getting rid of unnecessary paperwork and clutter after three months, one year and seven years, some documents should be kept on hand forever. learn what estate planning documents need to be stored forever

This is because they are so important that you may need to reference them at any point in time and it may be a good idea to keep copies and backups. These should always be stored in a safe location, such as a box that is safe from a fire. These documents should be maintained forever:

  • Personal identification documents like your social security card or birth certificate.
  • Income tax returns.
  • Legal documents such as lawsuit settlements, divorce and marriage certificates, and estate planning materials, unless they have been replaced by amended materials.
  • Loans for your car and vehicle titles. These should be kept for at least three years from the date the transaction is finalized. This information can prove helpful long after the transaction is finished, however, so you may wish to keep it forever.
  • Educational records such as transcripts, degrees and diplomas.
  • All major receipt purchases.
  • Any relevant financial planning documents and records, like pension plan documents, power of attorney designations, burial information, medical details, and living trusts and wills.

Talk to your estate planning lawyer to learn more about how to safely store these items.


Documents to Keep For At Least Seven Years in Your Financial and Estate Planning Process


It can be difficult to figure out which documents you’ll need to have on hand, which ones should be stored in a safe deposit box and have a copy at your lawyer’s office, and those that you can eventually get rid of after some time. learn what documents to keep for seven years

This is because there are so many different periods of time associated with holding on to particular documents, and in an effort to clear out clutter and ensure that you are legally protected in the event of a problem, you’ll need to be mindful of both. Some documents need to be kept for at least seven years before you can dispose of them safely. These include:

  • 1099 and W2 forms that can be used for tax audits and prove your income for loans
  • Tax related receipts which can become helpful if the IRS comes asking questions
  • Bank statements which should be kept for at least a year in electronic or printed form. These can be helpful if you have issues of identity theft, fraud or other challenges with your account.
  • Cancelled checks for mortgage, home improvement, business and tax purposes. Some people like to keep all of their cancelled checks, but this is an unnecessary process if you want to cut down on clutter.
  • Disability records or unemployment income stubs. Any paperwork you receive that is directly from the government related to an income source should be kept.

Consulting with an experienced estate planning lawyer in addition to other professionals on your team can be valuable for ensuring that you have the appropriate paperwork, and drafting the paperwork for your estate planning purposes when you don’t have it yet.

Documents to Keep for One Year: What You Should Know About Estate and Financial Planning

 Some documents need to be kept longer than the three-month period as discussed in yesterday’s blog. These should be stored in a safe location so that they can be accessed quickly in the event of a sudden problem, or in the event that your financial power of attorney agent needs to step in and make critical administrative or financial decisions on your behalf. 

These documents can be disposed of safely such as using a shredding service after a one-year period. These include:

  • Paycheck stubs
  • Monthly mortgage statements
  • Investment account statements
  • Insurance records and statements
  • Undisputed medical receipts and bills
  • Checkbook ledgers

Only hold on to these documents if you currently have a case dealing with the insurance company or a personal injury case.

After you receive your annual W2, there’s no reason to hold on to your paycheck stubs and your annual tax statements can be used in lieu of monthly mortgage statements. Investment account statements can include trade confirmations and monthly statements, but these materials don’t need to be kept longer than one year

Important Documents Series Part 1: What Should You Keep for Estate Planning Purposes?

Many people worry about having the appropriate documents on hand. In this four-part series, we’ll explore the various issues associated with keeping documents so that you know exactly what to hold on hand for the long term and what can be disposed of in a safe manner after an appropriate period of time. Certain documents should only be kept for three months or less. how long to keep planning documents

These might initially seem important or have personally identifying information on them, but they don’t need to be kept over the long haul and could actually expose you to a higher risk of identity theft if they’re floating around your home.

These may be good to keep for a couple of months, in case you become incapacitated and your financial power of attorney agent needs to step in. These documents to keep for 90 days or less include:

  • Utility bills
  • Receipts for everyday purchases
  • Credit card receipts
  • ATM receipts

Unless you have specific issues, like business deductions on your income tax return or company reimbursement practices, these receipts become inconsequential after a three-month period and can only add to the clutter in your office or your home. Your canceled checks or credit card and bank statements can be proof of payment for regular purchases and utilities. Certain documents need to be kept on hand for longer and we will explore these in tomorrow’s blog.

Will Less Planning Occur Because Of High Estate Tax Exemptions?

Do you think you don’t need estate planning?

Perhaps you did estate planning in the past, but you think that new high estate tax exemptions mean that it doesn’t make sense to engage in this process. 

Many estate planning attorneys and clients alike, were interested in how the most recent tax bill will play out. Although plenty of people are still digging into the mechanics of what this tax bill will actually mean for people planning on the ground, the high estate tax exemption is the subject of the most commonly asked question.

Taxes are at the front of many people’s minds these days, even more so than usual. The Tax Cuts and Jobs Act will double the gift tax exemption and the estate tax exemption. However, many estate planning attorneys expect to still find themselves helping clients of all types to put together an appropriate estate plan. The biggest anticipated growth in coming years is likely to be with income tax planning, with more than 45% of those attorneys expecting to see more work.

Just over one-quarter of estate tax planning attorneys expected to see less of this kind of work for estate tax planning purposes. Many believe that the current changes to the estate tax are not likely to last over the long run, meaning that people will eventually wind back up in their estate planning lawyer’s office.

What You Need to Know About Prioritizing a Dead Spouse’s Debts


When a spouse passes away, it can be an alarming discovery to realize that they have more liabilities than they did assets. Paying off these expenses can be extremely confusing for a spouse who was appointed as the personal representative of the estate. When an estate does not have appropriate assets to pay all of the debts in full, they must be prioritized. The first of these debts that should be paid are all funeral expenses and any of the expenses and costs associated with administration. 

If the funeral expenses were advanced by the surviving spouse, those can be paid back first. Furthermore, someone who is serving in the process of probating the spouse’s estate will be able to get reimbursed for the cost of administration, like legal fees. Next in line for debts to be paid are taxes that are entitled to preference under state or federal law. Hospital expenses and reasonable medical expenses are the next in line to be paid, particularly to the point that they relate to the final illness. If there are medical bills for treatment that was not related to the final illness, that is included in the remaining category of unsecured loans and credit card bills.

Every legitimate claim in a category should be paid first, before moving on to the next category. This can be a difficult situation for a spouse to find themselves in after the loss of a loved one when the grief and other elements of moving through the claim can be especially difficult. To understand your rights and to move forward with powerful knowledge about the future, schedule a consultation with an estate planning attorney.

What You Need to Know About the Survival of Dynasty Trust

If you are using trusts as part of your estate planning strategy, you are engaging with one of the most powerful tools for enhancing your privacy and control now and well into the future. Dynasty trusts have become increasingly popular in recent years as a tool for people to incorporate into their overall process. A trust gives a client the flexibility to change the disposition after a transfer. NJ estate planning lawyer

Even for many different clients who may be in the process of considering a dynasty trust when there is no estate tax, trusts are very flexible estate planning tools that also provide privacy and peace of mind for the person creating it. Dynasty trusts should always be drafted directly for the purpose of flexibility.

Merger, decanting, amendment and non-judicial settlements are all different possibilities to consider in a dynasty trust. A trust that allows a trustee to make distributions for beneficiaries with the absolute discretion assigned to that trustee may provide more flexibility than a trust that requires distributions made to beneficiaries with an ascertainable standard. All of these terms can be explained to you when you schedule a consultation with a trust planning attorney.

Trusts offer numerous different benefits for people creating the trust, as well as for your beneficiaries down the line. But because there have become so many options in the area of trust planning, a consultation with a lawyer is important to identify the tool that is most appropriate for your individual needs.

These Crucial Elements Should Be Included in A Business Succession Plan

Opening your own business is an exciting opportunity, but it is also one that requires thought about things that will happen long into the future in an ideal situation. Most people find themselves suddenly grappling with the problems of a business succession plan far too late. Putting their loved ones in the difficult situation of trying to figure out what to do with the company, and even whether they are legally empowered to take action with that company without all of the tools and implements necessary. Thankfully, doing some advanced planning with the help of a business succession planning NJ planning lawyer can give you a great deal of peace of mind and also provide clarity to your loved ones in the event that something suddenly happens to you. 
There are six critical elements of a powerful business succession plan that enables everyone in a power position to make the crucial decisions required when someone suddenly becomes disabled, wishes to exit the business or suddenly passes away. These six elements include:

  •   Beginning the planning process as early as possible even before the business owner has a clear idea for the exit plan.
  •   Structuring the plan with some flexibility to allow to evolve or change
  •   Bifurcating equity in control
  •   Diversifying the planning techniques used for the future of the business
  •   Transferring any tax savings
  •   Incorporating non-tax factors such as family harmony when the exit plan does include some family members but not others.

The right business succession planning lawyer is a strong advocate for the rights of the business owner as well as for the future of the company when engaged early.

Top Questions to Ask Your Estate Planning Attorney After the Passage of The New Tax Law


Now that the new tax law has come into place, plenty of people are thinking about what they need to do in order to protect themselves and their future. This often warrants a conversation with your estate planning lawyer, who can tell you more about what you need to know. An estate plan often needs to be updated based on your individual circumstances as well as shifts in state and federal laws. The aggressive tax reform that was recently passed should prompt you to schedule a consultation directly with an attorney. Ensuring that your plan is up to date can make things much easier for your loved ones in the future. The following questions should be considered by anyone who believes that an update to their estate plan may be in order. get help with 2018 tax laws by hiring a NJ estate planning lawyer

Even if you are not yet sure whether you need to revise your strategies or existing documents, a lawyer can help point you in the right direction and give you greater peace of mind about the future. These top questions include:

  • Will my estate tax picture be impacted by the new federal law?
  • How does my marriage or divorce get affected by the exemption limit?
  • Do I have to worry about any state estate taxes because of a property I own in other locations?
  • Are my estate documents customized to avoid unintended consequences and carry out my individual wishes?
  • How soon should I schedule another review of my estate plan?


The Best Gift You Can Give Is Investing for Your Heirs


Teaching your grandchildren and children to invest is an investment in their own future. This means you are passing down your own individual legacy and the financial expertise you have built over the course of a life time. This is why many grandparents and parents set up brokerage accounts to give family members an early start on investment opportunities.

Recent changes in U.S. tax laws, however, have changed the dynamics associated with multi-generational investment planning. It is often more important now for older generations to keep their appreciating assets with the primary purpose of helping their family members and beneficiaries avoid paying taxes on any of the gains. investing for your heirs is a powerful estate planning strategy

In the past, estate planning typically emphasized maximizing the annual exemption gifts and finding ways to get discounted values for gifts tax purposes on any assets that were transferred. However, in light of the new tax laws, currently on the books, investing for heirs now makes more sense. The ability to get a stepped-up basis at death has survived numerous versions of tax reforms.

This gives every member of the current oldest generation in the United States the opportunity to pass down assets to their beneficiaries that could avoid up to $11.2 million in potential capital gains. The best way to implement this strategy is to schedule a consultation with an experienced estate planning attorney and to hold the assets in your own name. You would then invest these as though you are holding on to them on behalf of your heirs. This may seem a more aggressive investment strategy than what you are used to, but younger investors will gain advantages because they do not have to worry about the same amount of market volatility that could impact an older generation.

Should You Increase Your Gifts Given to Your Children?


When thinking about passing on assets to future generations, a common question asked by many people is whether or not they should increase the amount that is passed on to their loved ones. With the passage of the tax cuts and Jobs Act, the lifetime exemption for estate taxes doubles to $11.2 million for individuals and $22.4 million for married couples. learn more about gifting with your kids for estate planning purposes

How you choose to pass things on to your loved ones can make things easier for you as well as them.

The lifetime gift tax exemption has also doubled to these same tax amounts. Gifting opportunities in light of these new regulations have to do largely with timing issues and magnitude. The previous increases in these laws have been much more gradual, making it more difficult for people to adapt their gift tax plans now. Consider the impact of a gift to your children on their lives, particularly when you intend to make the gift outright.

It is much easier for many people to pass on an asset or to write a check than to have a serious conversation about the various responsibilities that come with receiving wealth. There may be advanced issues in your unique family situation that should prompt you to contact an attorney about estate planning tools. These could include spendthrift children and addiction issues.

Consider Your Estate Planning as Some Decisions That Could Last for Many Years to Come

Consider that by the time you are reading this article, some people who have already articulated their new year’s resolutions, may have broken them. Whether or not you put forward new year’s resolution this year, you do have an opportunity in the New Year to make a decision that can impact you and your loved ones for many years to come. 

This decision has to do with your estate planning. Research shows that more than half of American adults don’t have any estate plan in place, including a basic will. This means that other people and mainly the court system, will be making decisions on their behalf.

If you don’t take actions to plan ahead, your loved ones are left dealing with the repercussions, all of which can be serious.  Going through probate can take time and add frustration to an already-hard situation, so it’s best avoided with the right planning. 

This can put your family members in a very uncomfortable and difficult situation after you pass away because your estate will likely need to pass through the probate system. The court is responsible for determining what happens to your assets and this means any individual wishes you may have had prior to an unexpected death were not recorded and will not be carried out. The decision-making process associated with estate planning is not always an easy one, but sitting down and investing some time into doing it can benefit your family for many generations to come.

Revocable Living Trusts and Tax Treatment

If you were thinking about putting together a revocable living trust, this can be a powerful estate planning tool. It is one often chosen by people who want to avoid the probate process.  

Numerous delays and expenses may be associated with your estate having to pass through probate, which prompts many people to put together a revocable living trust to make things easier for their loved ones in the future.

There are many different types of trusts, but revocable living trusts do not have a special tax treatment associated with them.

This is because the owner of this trust is still classified as the owner of the assets, so you will have to continue reporting income and earnings on your individual tax return as you did in the past. Revocable living trusts can help you avoid the problems typically associated with probate, but not those associated with the estate tax system.

A living trust may include provisions like language to generate a bypass trust upon someone’s death, but these same kinds of provisions are often included in wills or other estate planning tools. Talk to an experienced estate planning attorney today to learn more about the benefits of scheduling a consultation to put together a revocable living trust.

Top Concerns for High Net Worth Clients in Light of New Tax Changes

Many people are taking the opportunity to look at their current estate plans and tax plans in light of new tax laws in the U.S. While everyone can benefit from a regular review of their estate planning tools, high net worth clients have the most to gain from setting up a time to talk about estate planning and asset protection planning.

There are a number of different tax implications for wealthy families currently facing the restructuring of their estate and tax plans. Trusts can provide valuable protection from divorcing spouses and creditors and also enhance the control of an individual over how a beneficiary inherits wealth. 

This is particularly important for families that have addiction, mental illness, or spendthrift considerations. Furthermore, trusts can be used to help preserve wealth for numerous generations.

Since numerous different states will have their own estate tax regimes and you may own property in multiple states at the same time, anyone who owns property or resides in those states should continue to plan around these state level taxes.

For very high net worth clients who still have exposure to the federal estate tax or live and own property in states with their own estate tax, traditional wealth transfer strategies identified by an experienced estate planning lawyer can be helpful.


The New Tax Laws and Property Taxes In New Jersey

Are you getting ready to file your tax returns in New Jersey? Many people who rushed to pay their 2018 property taxes before December 1st will not be able to deduct this expense from their 2017 state income taxes, according to research from the New Jersey Society of CPAs. The IRS recently issued instructions that certain 2018 pre-payments were deductible from federal income taxes in 2017. plan for taxes and estates with a lawyer

While this is true at the federal level, the same is not true for state income taxes. Homeowners may be in for an unfortunate surprise when they realize that their attempts at end of year planning to increase their federal property tax deduction will have no impact on their exact 2017 New Jersey income tax returns.

Setting aside a time to talk to an experienced estate planning attorney in New Jersey can give you a great deal of peace of mind and clear planning strategies for your best interests. You need to look to the year ahead and ensure that you’re using strategies that both work for you as well as truly protect your interests.

It can be a minefield to try and decipher tax laws on your own. Thankfully, however, with the help of a lawyer this process can be made that much easier. Sitting down with an attorney and walking through your current strategies to identify whether or not they will still work for you is a valuable exercise and one you should consider carefully.

How Assets Are Distributed: What You Must Know

If you do not have an estate plan, the state will create one for you by intervening on your behalf. When you pass away, virtually all of your assets are distributed in one of the following ways. learn what happens to your assets when you pass away

These can include:

  • By state law or by will: Anything that isn’t distributed by beneficiary or by ownership will pass through state law. Many people believe that they don’t need a will because they will assume that their spouse will receive everything by ownership or by beneficiary. While that may be true, if both of you were to suffer in an accident together, this can raise significant questions.
  • Beneficiaries: You usually will name beneficiaries on life insurance plans, health insurance, savings accounts, and retirement plans. These will pass outside of the probate system because they refer to the specific paperwork you filed directly with those account managers.
  • Ownership: If your property was owned by joint tenants with survivorship, the asset will immediately be transferred to remaining surviving owners. If you own your home with a spouse, for example, the spouse will automatically get it. However, you may have other real estate interests that have not been clearly laid out in your estate plan.

You need to consult with a knowledgeable attorney who can help you navigate this process and ensure that you have considered all potential angles in putting together your estate plan.


The Top Four Retirement Risks

As you look ahead towards your own retirement, do you think you’ve done enough planning? In volatile times, it’s hard to tell what kind of risks you might face years into the future when it’s time for retirement. You need the support of a team of professionals who can help you guard against major retirement risks. 

A solid income plan should always be used to avoid problems with your retirement. If you thought that saving for retirement was difficult, your nest egg needs to be protected well after you reach age 65 or the age at which you intend to retire. Some of the most common risks include taxes.

If you have a silent partner in Uncle Sam because you have been putting away money in a tax-deferred retirement plan, you could be putting yourself at risk for less income than you expect. In addition, investment risk, inflation risk, and legacy and estate risk can all pose problems for you, if you do not have the assistance of an experienced estate planning attorney. When you know how you intend to get to retirement and what you will do to protect your assets once you get there, you will feel much more confident in the management of your estate and the fact that you have done everything possible to minimize potential risks.

Top Things Entrepreneurs Get Wrong in Running a Business

There are so many different risks to think about and potential growth opportunities affecting entrepreneurs that far too many of them fall prey to missing out on important planning opportunities. One of these includes not preparing for a lawsuit well before it happens. Most entrepreneurs only worry about this after a lawsuit has been filed or after an accident has occurred. However, at this point, options are limited.

Being an entrepreneur comes with a long to-do list, but it’s still important to consider that protecting your risks is a worthwhile endeavor. Asset protection planning is one worthwhile goal. 

Some advanced asset protection planning carried out with the assistance of a lawyer can help you. You don’t want to commit what is known as a fraudulent conveyance, such as moving money around to avoid losing it to a lawsuit once the lawsuit has already been filed. The best time to plan for asset protection planning is when there is no risk in sight. If you plan appropriately, you may be able to settle lawsuits for very little compared to the potential exposure.

The crucial aspect of this is having a comprehensive plan drafted by an estate planning attorney so that those assets cannot be taken from you.

What Did Whitney Houston, Michael Jackson And Prince All Do Wrong?


The deaths of icons Whitney Houston, Michael Jackson and Prince rocked the world, but unfortunately, left their families burdened and broken-hearted with estate taxes and fees. Despite having professionals to help with practically every aspect of their lives, none of these artists had a total estate plan, which ultimately ended up costing their heirs millions of dollars and what would have otherwise been avoidable taxes and legal fees. avoid these estate planning mistakes

An estate plan is crucial for the peaceful transfer of assets from your generation to the next. However, even if your estate doesn’t include things like private amusement parks or music rights, there are still takeaways from these artists’ situations to avoid the same costly mistakes. Even though Prince, for example, had paid all necessary taxes without audits from the IRS and had appropriately valued assets, he left no will when he died.

This means that more than 45 people ultimately came forward claiming to be heirs, including nieces, half siblings, siblings and supposed children, which cost the estate tremendous amounts in legal fees to investigate this and respond to it. In order to avoid these challenges, schedule a consultation with an experienced estate planning attorney, regardless of the size of your estate. You can get your own peace of mind and ensure that your beneficiaries receive the assets to which they are entitled well in advanced.