Inheritance Taxes and State Estate Taxes

On top of federal estate taxes to which your estate can be subject, you may also need to plan in advance for state estate and inheritance taxes. As far as inheritance taxes go, six states use these to obtain funding from assets passed on to heirs. In the past, state estate taxes largely weren’t an issue for most of the population because the federal government gave an estate tax credit based on how much was already paid into state taxes. Now it’s largely up to the states, and if you’re a resident in one where your assets could be subjected to a pretty substantial hit, it’s simply prudent to plan in advance.
Inheritance Taxes and State Estate Taxes
(Photo Credit: dot429.com)

The state thresholds aren’t so high that many people can be exempted, either: New Jersey’s exemption stops at $675,000. Factoring in the value of many people’s homes, retirement accounts, and other assets, it’s not hard to surpass that. And New Jersey is a double whammy- state taxes and inheritance taxes apply there, so it’s very common for individuals and business owners especially to consider their planning options well in advance.

The good news is that there are strategies and opportunities to identify and mitigate risk, but they do depend on your state. You want to find a professional that is up to date on all relevant state laws and regulations to ensure that your estate is protected properly. Contact us today to begin or to review your existing plans by email at info@lawesq.net or at 732-521-9455.
Durable Powers of Attorney and FBAR

A new reference guide from the IRS has some guidelines for Reports of Foreign Bank and Financial Accounts (FBAR). There are several issues highlighted in the reference guide that give cause for concern (or for a call to your business planning and tax strategy specialist), but one to note is with regard to durable powers of attorney.

Durable Powers of Attorney and FBAR
(Photo Credit: wtas.com)

Durable powers of attorney are a foundation in a great deal of estate planning, especially when it comes to business owners who either want to preserve their legacy or protect the business and/or a partner in the event of an incapacity. Most of these powers of attorney stipulate authority to sign on behalf of the principal for bank accounts belonging to that individual.

An evaluation of the new Reference Guide reveals that under the description of signature authority, individuals named in those powers of attorney may be at risk for penalties related to foreign accounts of the individual issuing the power and those individuals may inherit responsibility for FBAR filing.

It’s unclear whether a lack of knowledge argument will be applicable in such a scenario, so it’s in the best interest of named parties to be aware of their rights and responsibilities. Since that’s not always possible or reasonable, an estate planning specialist can discuss options directly with the individual creating the durable power of attorney.

To learn more about asset protection, business planning, and risk mitigation, contact us today by phone at 732-521-9455.

Time for New Jersey Residents to Reconsider the DING Trust

In light of today’s federal and state income tax environment, those living in high income tax states, like New Jersey, are always looking for options to understand and mitigate risk exposure. In the event that you are influenced by a state income tax, the hit can be substantial. Knowing how to use current strategies is highly valuable for anyone in this situation.

Time for New Jersey Residents to Reconsider the DING Trust
(Photo Credit: irs.com)

The IRS has recently made it a little easier to mitigate such risks through the use of a DING Trust, which stands for Delaware Incomplete Non-Grantor trust. In a DING trust, a person can transfer assets are produce high levels of income into a trust. This transfer doesn’t trigger federal or state gift taxes but it also minimizes the exposure to state income tax. The purpose of such a trust is to transfer these assets into a bucket in a state without trust income taxes, like Alaska, Nevada, and Delaware.

This particular kind of trust is best used with someone who maintains high levels of income generating portfolios. For New Jersey individuals in this situation, it’s important to note than an investment portfolio held inside a DING trust is exempt under the state and local income tax so long as the trustee is not a resident of the state of New Jersey. Alongside other estate planning strategies to reduce the overall taxable estate, the DING trust is most appealing to New Jersey residents concerned about the influence of the state income tax. To get started with DING trust planning, contact us through email at info@lawesq.net or contact us via phone at 732-521-9455 to get started.

Minimize Estate Taxes Through Gifting

Your estate planning goes farther than figuring out who should be named as a beneficiary and how much they should receive. Comprehensive planning also thinks about the best way to distribute assets and how the methods you choose influences the beneficiary’s life.

Minimize Estate Taxes Through Gifting
(Photo Credit: bloomberg.com)

On your death, your estate is subject to Generation Skipping Tax and Estate Tax. In states like New Jersey, your estate will also be subject to a State Estate Tax plus an Inheritance Tax in some cases. Without realizing the impacts, a portion of your estate can be swallowed up before your beneficiaries ever receive it. Some states also impose their own estate tax, diminishing your estate even further. The good news is that some advance planning with a professional can reduce the impact of these taxes.

To start with, you can take advantage of the federal exemption amount of $5.34 Million, which allows you to give away up to that amount during lifetime and death (total) without initiating that estate tax. Annual exclusion gifts, too, can be helpful for minimizing the blow of a big tax. Married couples are able to combine exclusion powers to give up to $28,000 per year per person without being hit with a tax, and this is separate from the federal gift-tax exemption.

This is just the tip of the iceberg when it comes to strategies to protect wealth and minimize taxes. Many tools are available and you can learn more from contacting us today for a consultation. Send us a message at info@lawesq.net or contact us via phone at 732-521-9455 to begin.

It’s not all about the cash: Passing on Wealth and Wisdom

It might feel overwhelming to put together your estate plan, but it’s a good tool for you as well as your children. Taking care of your needs early on can encourage children to plan for the long term and to consider their own estate plans. One of the biggest hurdles with regard to estate planning, in fact, is that there’s a general stigma when it comes to talking about money. Simply setting aside some time for the conversation is a valuable process.

Its not all about the cash Passing on Wealth and Wisdom
(Photo Credit: danielharkavy.com)

Many people that estate planning is simply for the management of their assets after they pass away, but that’s simply not true: it plays just as vital a role during your life, too. If you become incapacitated, a comprehensive estate plan will lay out your wishes clearly for your family members and other stakeholders. It’s also a tool that can be used to reduce risk and minimize taxes while protecting wealth- all of which are just as valuable while you are living.

One mistake to avoid in thinking about your estate planning is in seeing your wealth only for what it can do for the next generation in a positive light. Sometimes, there’s another impact that’s often forgotten- what your assets do to them when it comes to unintended consequences. Taxes can take a big hit on the assets if plans are put into place in advance, and gifts may even cause arguments between family members. Not every child, for example, will react the same way to learning that Mom or Dad has left a gift behind.

Estate planning is just as much about your mindset and passing on your wisdom as it is your wealth. To help create a living legacy that makes the most sense for your family, call us at 732-521-9455 or reach us through email at info@lawesq.net .

Guardianship for a family member with Alzheimer’s

May was celebrated as Elder Law Month, and as the baby boomer generation ages, guardianship of an elder may be a growing concern. Although guardianship is most often discussed regarding minor children, it can be a helpful tool for older family members, too.

Guardianship for a family member with Alzheimers
(Photo Credit: medcitynews.com)

One in three people age 65 or older will contract some form of simple disability (cognition, vision or hearing impairment, the inability to get around without assistance, etc.). A diagnosis of such a disability may highlight the difficulty that individual faces in daily living. More difficult than basic aging or simple disability is the presence of Alzheimer’s; according to the Alzheimer’s Association five million are living with it presently, at a cost in 2013 amounting to $203 billion.

Being watchful for thesigns of Alzheimer’s can be an important step in recognizing the need to consider guardianship: among them, memory loss affecting daily living; the inability to complete familiar tasks; misplacing things; confusion over either time or place.

If the elder person does not have a power of attorney or advance directive, you can go into court and seek a declaration of incompetence. Subsequent appointment as a guardian will mean assuming decision-making for living arrangements, the management of finances and medical choices–the last two critical as out-of-pocket costs for older Americans have jumped 46 percent since the year 2000.The guardian has the legal duty to act in the best interest of the ward, and only in those areas permitted by the court. Those looking into guardianship for older parents may want to evaluate their own estate plans at the same time.

Difficulties may extend or render contentious the achieving of a guardianship role. If other family members cannot agree on the need, or on the proper person, the process can be lengthy. Further, the elder individual has the legal right to contest, and the determination of the court will only follow upon extensive expert evidence. Planning for your needs in advance can be extremely helpful for reducing family conflict. To learn more about applying for guardianship in New Jersey or planning to avoid the need, reach out to us at info@lawesq.net or contact us via phone at 732-521-9455.

Tax and Structure Considerations for Buy-Sell Agreements

A buy-sell agreement needs to be written properly in order to ensure that it’s effective for invested parties. There are some specific aspects that should be considered in the planning of any buy-sell agreement. Here are some of the basic stipulations:

Tax and Structure Considerations for Buy-Sell Agreements
(Photo Credit: yoursmartmoneymoves.com)

  • The commitment of involved parties. The obligations of each party should be outlined clearly, leaving no room for questions
  • The purpose of the arrangement should also be specified
  • A formula explaining the purchase price of the business interest should also be included, like a value for the selling/buying price for the business. Furthermore, how this should be funded is also explained.
  • Any transfer restrictions should also be included, which can prevent the owners from transferring interest in the business while any other parties to the agreement are still alive.

Bear in mind that there are tax considerations for funding a buy-sell agreement with life insurance, such as:

  • Premiums used to fund the agreement are generally not tax deductible
  • There’s no gift tax that happens on the buy-sell agreement execution
  • In a cross purchase agreement, the cash value of the policies that are owned by the decedent can be factored into the decedent’s estate.
  • Death proceeds are paid out income-tax free, no matter who actually owns the policy.

If you’re planning on structuring such an agreement, you might use an entity purchase agreement, a cross purchase agreement, or a hybrid agreement. To learn what will work best in your situation, send us an email at info@lawesq.net or contact us via phone at 732-521-9455.

Special Planning for Second Marriages: Lessons Learned From Casey Kasem

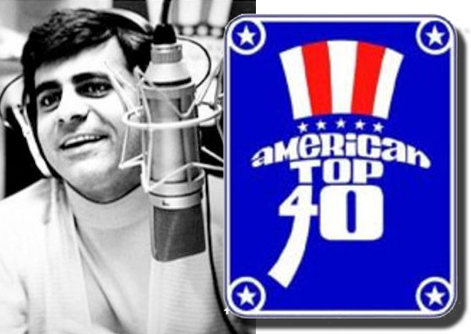
The recent news hoopla over Casey Kasem illustrates an important lesson for planning your own estate: things may change when you throw a second marriage into the mix, calling for a re-evaluation of your plans. There are many things that should be addressed in estate planning where a second marriage has occurred. Doing so will help prevent problems and lay the groundwork for plans that actually carry out your wishes rather than spark legal battles among family members.

Special Planning for Second Marriages Lessons Learned From Casey Kasem
(Photo Credit: mediaconfidential.blogspot.com)

Medical directives, powers of attorney, and even decisions about burial planning should all be considered in your estate plan if you are involved in a second or third marriage. This avoids conflict between family members that can make the grieving process even more difficult.

When it comes to passing down assets, this is especially complex in a second marriage. Who should get the money? Should it be split between children? Does it go to the first wife in one lump sum and the remainder is split among the children? There’s a lot of tension that can arise if you don’t think about the answers to these questions well in advance. Conflicts tend to crop up especially when a non-parent spouse is receiving assets that children feel entitled to in one sense or another. The more clarity there is in your planning, the better. Once you’ve met with an estate planning professional, it’s important that you in some sense communicate what you have outlined to family member stakeholders. To learn more about estate planning techniques for second and third marriages, email us at info@lawesq.net or contact us via phone at 732-521-9455

Estate Planning For Your House: Irrevocable Trusts

A transfer of assets outright may not be the best solution as this has been known to create undesirable outcomes. In the case when planning to avoid probate and conservatorships, it makes more sense to use an irrevocable trust. In many cases, the biggest and/or most important asset to be transferred is a home.

Estate Planning For Your House Irrevocable Trusts
(Photo Credit: nwkidsmagazine.com/2012/01/1560/)

An outright transfer could cause problems: if it ever becomes necessary or desired to sell the property to buy a new one elsewhere, this can be difficult. Also the new owners might lose the residence to creditors or divorce or sell it on their own. That’s why it may be preferable to use an irrevocable trust to ensure protections and flexibility in planning. This can be done using lifetime retaining benefits held by the transferor.

There are benefits to using an irrevocable trust to manage the house transfer. First, the residence is protected from the threats of creditors or ex-spouses of death beneficiaries or the trustee. Second, if there is interest or need to sell the home to acquire a new one, the trustee can navigate this move fairly easily, If drafted properly. To talk more about how to plan for the transfer of your home, we can help. Email us at info@lawesq.net or contact us via phone at 732-521-9455.

Your IRA: Top Tips For Passing Down Your IRA To Children

Those who have spent a good amount of time contributing to their IRA might have questions when it’s time to decide beneficiaries. For example, is it best to stretch out the payouts over a lifetime to make the most of tax benefits or to withdraw the entire amount?

Your IRA Top Tips For Passing Down Your IRA To Children
(Photo Credit: beginnersinvest.about.com)

In many cases, an immediate emptying of the account is not in the best interest of the beneficiary, and it’s also something that parents may want to help their children avoid. Often, it’s difficult to suddenly manage a large sum of money, making Mom and Dad’s IRA benefits run out long before expected. Since many parents want to guard against this where possible, it’s important to note that two different strategies can help to stall an immediate withdrawal of all assets on the death of a parent.

One option is to name a trust as the IRA beneficiary, giving a trustee the power to distribute assets, but you must work with an experienced estate planner who knows how to craft a document that qualifies under IRS rules. Another option to consider is setting up the IRA as a trust account, giving trustee powers to the IRA provider, which is known as a “trusteed IRA”. This option, however, does have some downsides: higher fees and requirements for minimum balances are two of those disadvantages.

Options exist to help you plan for your future and to help beneficiaries receive assets in a somewhat-structured manner. To learn more about these planning tools, call us at 732-521-9455 to get started.

Married Couples without Children: Estate Planning Recommendations

Your individual estate plan is going to depend largely on your personal situation and the goals you have for your assets. That being said, one major factor that can alter your estate planning situation tremendously is children. Without children, some couples might wonder what estate planning options could be used.

Married Couples without Children Estate Planning Recommendations
(Photo Credit: lancewoodley.com)

One such example is a QTIP trust, or a Qualified Terminable Interest Property Trust. This trust gives a benefit to the surviving spouse that keeps the assets out of the hands of creditors. Using this trust properly, assets from the trust that are still present after the surviving spouse passes away would then be given to beneficiaries stipulated by the spouse who passed away first.

A big benefit to this approach is that the personal representative of the first spouse (referring to the spouse who passes away first) can exert some flexibility over the best way to proceed. A partial QTIP election or portability election are the choices that a personal representative might consider after the first spouse passes away. One factor to bear in mind is ensuring that the applicable exclusion amount of the first spouse doesn’t go to waste, which can be addressed in planning strategies with your estate planning specialist.

Your family structure and how involved your family is in your own estate plans strongly dictates what needs you have when you come to the table to discuss your goals and concerns. To learn more, email us at info@lawesq.net or contact us via phone at 732-521-9455.

An S Corporation Tax Strategy: Can You Eliminate Current Income Taxes on Company Profits?

In a recent article by the Wall Street Journal, a potential possibility for limiting tax liability is being considered on the heels of the two North Carolina business owners who are attempting it. Right now, the issue is being explored in U.S. Tax Court, too, where a previous decision in December issued a ruling in favor of business owners.

An S Corporation Tax Strategy Can You Eliminate Current Income Taxes on Company Profits
(Photo Credit: socaladvocates.com)

In an S Corp, which is typically how closely held firms organize themselves, earnings go directly from the company to the owners, who then have to pay taxes on their individual returns. This only works for companies with less than 100 shareholders, but it does provide a shield of corporation-like protection while avoiding an income tax at the corporate level.

Depending on how the court decides, there are major ramifications ahead for S corps. If the decision is handed down in favor of the corporations, these organizations may be able to reap significant tax savings by limiting their liability. In the North Carolina case, it’s all about how the owners structured their agreements. They reorganized the company into an S Corp in 1998 with a divided ownership strategy that gave 5 percent ownership to an ESOP. These assets can increase in value tax-free and allow for penalty-free withdrawals by individuals at age 59 ½ .

For tax purposes, nearly all of the profits from the corporation could have been shifted to the ESOP, putting off tax liability until individual withdrawal down the road. Many corporations are interested in mitigating risk and exploring tax reduction strategies, we can help with both. Email us at info@lawesq.net or contact us via phone at 732-521-9455 to get started.

Preventing End of Life Costs from Destroying Your Estate

It’s very rare that anybody has covered all possible risks in terms of their wealth management when it comes to income and cash flow, guaranteed income, cash, investments, and the connection between long term care and your estate. If you skip planning for long term care expenses, you may find that your other wealth management tools and strategies don’t hold up to the rising cost of healthcare.

Preventing End of Life Costs from Destroying Your Estate
(Photo Credit: colourbox.com)

The average cost per month for a long-term care facility is over $7,000. That’s why long term care planning is so essential. When a long-term care insurance policy is too expensive or not an option because you do not qualify.

There are alternatives, however. Structuring your estate in a particular manner can help you guard against the cost of long term care. Two common strategies are eliminating assets through trusts and transfers. This means that down the road, if you need to reduce your assets for Medicaid eligibility, you’ve already done most of the work. If you are confronted with a long-term care event before you have done this, you could find yourself having to “spend down” your assets anyways before government assistance kicks in, depleting your savings and forcing you to do it rapidly, which is rarely in your best interest. However, if you do it incorrectly, it has the potential to have a severely negative impact on eligibility and penalty periods. To learn more about trust planning, gifting, and other strategies to mitigate risk in estate planning, email info@lawesq.net or contact us via phone at 732-521-9455.

Changing Your Power of Attorney

What if you already executed a power of attorney some years ago and now want to change that person? Is it as simple as revoking the old one and creating a new one? Make sure you’ve investigated whether your power of attorney is “durable” or “springing”. What’s the difference?

Changing Your Power of Attorney
(Photo Credit: monkeyoffyourback.com)

A springing POA is a person who has not yet assumed his or her position yet, making it much easier to change your plans. If you named someone else as a backup and would prefer that person now be your POA instead, you can amend your existing power of attorney to reflect this change in plans.

If the POA is actually a durable attorney, meaning that this individual was empowered to act on your behalf immediately after the document was executed, you may need to do a little more work. You should use certified and first class mail to notify the original individual that he or she has been removed as POA in case there is a dispute down the line about termination and institution of a new POA. If you believe that this person is out there exercising authority under your old Power of Attorney, you’ll need to take responsibility for contacting banks or other institutions where this is an issue. Make sure you have your estate planning attorney keep copies of all your documents on file in case there are any questions. To begin or change a power of attorney and any other estate planning documents, call us at 732-521-9455 today or request a meeting via email at info@lawesq.net.

Banking on an inheritance? Don’t count your chickens before they hatch!

New research from the Insured Retirement Institute shows that although nearly two-thirds of older individuals considered leaving an inheritance behind important in the past, those numbers have shifted out of beneficiary favor. According to their report, less than half of baby boomers today believe it’s critical to leave behind an inheritance.

1
(Photo Credit: greekweddingtraditions.com)

So, what’s behind this big shift in attitude? Many older individuals and couples want to see that you are capable of handling an inheritance first, taking the following factors into consideration:

  • A pattern of good financial decision-making skills. This doesn’t mean you’re mistake free on your credit report. Parents just want to see improvement and a pattern of it to verify that you’re responsible enough to handle a lump sum inheritance.
  • Understanding of your own financial missteps and accomplishments. Once again, it’s not about being perfect. Some older parents thinking about an inheritance left behind want to know that you’ve made your mistakes, learned from them, and moved on. It’s a sign that you’re growing in terms of financial independence and understanding. If you have a pattern of racking up debt and then struggling to pay it off, however, that’s not a good sign.
  • Debt awareness. Are you making student loan payments? That’s okay, because it was an investment in your future. Credit card debts and big car loans, however, show that you might not be familiar with the right kind of debt- or the right way to pay it off. Both are red flags for parents.
  • Educate yourself. No need for a post-graduate degree here, but certainly some financial education on your own through books, planning, and even videos can be really helpful. Find out your weak spots and work to improve them on your own. This shows ambition and desire, both of which parents love to see.

There’s never been a better time to get started. To discuss your plans for asset protection, tax minimization, and your estate, email info@lawesq.net or contact us via phone at 732-521-9455 to get started.

Will your good deed go unpunished?: Limiting nonprofit individual liability

A common question from trustees, officers, directors and volunteers at nonprofit organizations is to what extent these individuals face liability as representatives of the organization. Failure to adhere to tax formalities or mismanagement can, in some situations, make an individual person liable. In this instance, asset protection for the officer and direct is vital in addition to insurance.

Will your good deed go unpunished Limiting nonprofit individual liability
(Photo Credit: greekweddingtraditions.com)

Typically, lawsuits of this kind happen in one of a handful of ways:

  • An error or omission resulting from a trustee, officer, or manager’s decision (or lack thereof)
  • An allegation regarding corporation activities I which the director, officer, or trustee was not involved
  • An allegation of corporation activities in which the trustee, director, or officer was involved

There is a lot at stake in a lawsuit of this type, especially when the other party is alleging serious professional negligence that leaves an individual officer or director exposed to a high level of personal risk. Errors and omissions claims, which happen most often when a nonprofit organization has very little resources compared with what the claimant hopes to receive in damages, can devastate a nonprofit. These claims result from situations in which a nonprofit officer or director is held responsible for a decision or lack of decision in a particular situation. For example, a nonprofit event where an individual person is injured could lead to a lawsuit about the nonprofit’s decision to hold the event in the first place.

Thankfully, there are approaches you can take to mitigate this risk. This includes carrying errors and omissions insurance, carrying liability insurance, managing the affairs of the nonprofit as a corporation, and providing for partial or complete indemnification of officers and directors through specific agreements and don’t forget your asset protection planning. Some careful planning in advance can go a long way towards limiting lawsuit exposure. Contact us today through email at info@lawesq.net or via phone at 732-521-9455 to begin your asset protection plan.

New York Tax climate improves slightly, according to Tax Foundation

An estate that is worth more than $1 million is a bit more common in New York than in other states, but for much of recent history, those residents were hit with a 16 percent state tax on their estates. This led to many New Yorkers moving out of state to more tax-friendly locations to ensure that heirs were able to keep as many estate assets as possible. Recognizing the drain of these estates to other locations, legislators have implemented a gradual plan making golden years in New York much more attractive.

New York Tax climate improves slightly, according to Tax Foundation
(Photo Credit: spiritualcommons.org)

Every year until 2019 the exemption will increase based on what day the individual in question passes away. Since small nuances in the law and a minor mistake could lead to bigger tax consequences, those with estates above $1 million should conduct an annual review of their tax planning to verify asset maximization. Even being off by one cent can throw off an entire plan, so it’s vital that regular review and analysis are used to help protect the estate. The new exemption is increased by $1,062,500 every year until reaching the federal exemption amount in 2019. At present, some New Yorkers have looked to DING and NING trusts, those trusts held in other states to reduce tax consequences.

This move, combined with estate tax changes that exempt small businesses from massive taxes after an owners death and decreases in the state’s corporate tax rate, were applauded by the tax policy research organization Tax Foundation. The organization noted that it these were important steps towards improving the reputation of ease of doing business within the state. All of the recent changes were adopted in the most recent state budget, details of which were released at the end of March. Special planning for New York tax liability can be completed by an estate planning specialist. For tax planning strategies, email info@lawesq.net or contact us via phone at 732-521-9455 to get started.

Side Business? Silent Partner? What’s the Risk? Duties of non-manager members of LLCs

If you are interested in creating a managed multi-member LLC, one of the most popular questions for individuals in this position is whether non-manager members are held to the same standards (or have the same liability) with regards to fiduciary duties like care and loyalty. The answer is “it depends”.

Side Business Silent Partner Whats the Risk Duties of nonmanager members of LLCs
(Photo Credit: serpent.com)

In the non-manager members are involved in some significant aspect of the business, the operating agreement should generally include an expression of such duties for these individuals. Looking at the landscape of typical non-manager member involvement in the business of these LLCs, significant duties are typically rare with smaller businesses that are closely held.

There are some cases where the operating agreement might not address this question specifically. In this scenario, the LLC act governs and can provide some important insight. A lot of these acts, however, are quiet when it comes to this particular question. Some agreements, however, do have specific information about these duties included. An example is the Delaware Limited Liability Company Act, which actually negatives any duties for the non-manager members unless an express clause in the LLC agreement states anything to the contrary.

LLC formation and agreement construction can be aided significantly with the watchful eye of an attorney. Call us at 732-521-9455 or send us an email to info@lawesq.net to discuss your needs.

Side Business? Silent Partner? What’s the Risk? Duties of non-manager members of LLCs

If you are interested in creating a managed multi-member LLC, one of the most popular questions for individuals in this position is whether non-manager members are held to the same standards with regards to fiduciary duties like care and loyalty. The answer is “it depends”, but with a few stipulations.

LLC practice - fiduciary duties of non-manager members of multi-member LLCs
(Photo Credit: serpent.com)

In the non-manager members are involved in some significant aspect of the business, the operating agreement should generally include an expression of such duties for these individuals. Looking at the landscape of typical non-manager member involvement in the business of these LLCs, significant duties are typically rare with smaller businesses that are closely held.

There are some cases where the operating agreement might not address this question specifically. In this scenario, the LLC act governs and can provide some important insight. A lot of these acts, however, are quiet when it comes to this particular question. Some agreements, however, do have specific information about these duties included. An example is the Delaware Limited Liability Company Act, which actually negatives any duties for the non-manager members unless an express clause in the LLC agreement states anything to the contrary.

LLC formation and agreement construction can be aided significantly with the watchful eye of an attorney. Call us at 732-521-9455 or send us an email to info@lawesq.net to discuss your needs.