Why You Need to Have a Conversation with Your Elderly Parents About the Difference Between a Will and Beneficiary Designations

Unfortunately, some adult children find out too late that their loved ones did not take all the necessary steps as it relates to estate planning. This can compromise the integrity of what the decedent wanted to pass along particularly if the will was updated but the beneficiary designations on bank accounts, retirement accounts or life insurance policies were not. will and beneficiary designations
The companies that have those beneficiary designations are responsible for adhering to the last filed materials by the decedent, meaning that even if the will stipulates that someone is to receive half or all of the overall estate, those beneficiary designations are cleared separately. This means that if a person did not update their life insurance policy and a spouse they had divorced from is still listed as the beneficiary, that individual would still be entitled legally to receive any and all benefits under that life insurance policy to which they were previously entitled.

It is extremely important to ensure that your loved ones update their documents on both ends as it relates to estate planning tools like wills as well as beneficiary designation forms including those with life insurance policies. Consulting with an experienced estate planning lawyer can help you accomplish this goal. It is essential that your parents understand that these are two separate things and they both should be updated if they intend to update their estate plan purposes overall.
 

Liquid vs. Illiquid Assets to Leave Your Loved Ones

Estate planning is about more than deciding that you want to leave things behind to your loved ones- it’s also about deciding what you’ll be leaving behind and how it makes the most sense for your family members and friends. What they are able to do with those assets could have a big impact on their future. leaving behind assets to your loved ones

Taking an inventory of all of your assets while you are still alive allows you to determine the best strategies for your estate planning overall. You might decide that some of these assets should be gifted to individuals while you are still alive or placed inside a trust for the purposes of asset protection or estate planning.

Consider liquidity as well when you determine what assets you would like to leave behind to your family members. A liquid asset is any asset that can easily be converted to cash with little impact on the price of that asset. if your estate is mostly made up of hard assets, your heirs may be forced to sell these for a discounted price in order to raise the funds necessary to pay for the estate tax.

Considering all of these complex issues is much easier when you identify a New Jersey estate planning attorney who has extensive experience in this field. Do not hesitate to reach out to an experienced New Jersey estate planning lawyer to talk more about the assets you intend to leave behind and the most appropriate strategies for doing so.


How to Effectively Approach Your Digital Accounts Before You Pass Away

There’s plenty of discussion about the benefits of traditional estate planning but you may also need to consider how your digital accounts are included as well. Most people underestimate the number of digital accounts that they truly have. Choosing to inventory these and listing all of the appropriate passwords and username information can make it easier to identify what you want to happen to them after you pass away. 

There’s a good chance that you’ll have different plans for different accounts. For example, you may wish to memorialize your Facebook account but have other accounts closed entirely. If you do not follow the terms of service listed on each individual website, however, your digital executor may face challenges trying to carry out your wishes. Bear in mind that each website might have its own rules requiring your executor to show proof that the action they intend to take is in line with what you wanted to occur.

Getting the proper documentation well in advance by consulting with an estate planning attorney can help you with this. You can also help avoid some of these challenges by backing up your files. Downloading all of the digital assets to an external hard drive, for example, will make it much easier for an executor to access after you pass away. Make sure that every time you add a social media or other digital account that you add this information to your records. Make sure you note accounts that you have set to auto delete after a certain period of inactivity. This will make things much easier when you approach the estate planning process.

Asset Protection Planning: Thinking Ahead When You Get Married

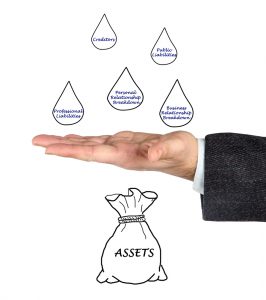
Divorce is not inevitable but many people find the process of thinking about their future finances and ending their marriage as extremely difficult when they are just planning the wedding itself. However, a strategic wealth plan can be an important component of asset protection planning. asset protection planning goals


Divorce is a risk that every marriage faces. It is strongly advised that every individual thinking about getting married consider asset protection for their own sake as well as for the future of their children and future generations. The best financial protection that an individual who has any significant wealth entering into a marriage can provide is to put together an asset protection trust or classify a dynasty trust.


Other multi-generational wealth planning tools can also be advantageous. This protection can help remove the wealth from the hands of future creditors, future ex-spouses, inappropriate beneficiaries or lawsuit decisions. This can also help individuals to avoid starting a marriage without having the uncomfortable conversation about prenuptial agreements.

Asset protection planning is an important topic that parents should always consider, as well as any couple that intends to protect their assets from unintended consequences. There are several different types of assets that you can protect in the process of asset protection planning including:

  •       Real estate
  •       Financial gifts
  •       Inheritances

Having the assets protected inside a domestic asset protection trust or an irrevocable trust is strongly recommended.   


Planning Ahead if You Intend to Give Assets to Your Children Differently in Your Estate

Although the most popular way to approach your estate plan is to leave all assets equally to all your children. However, there are many situations where parents might apply logical reasoning to determine that unequal inheritances are a better approach. For example, if you have a child with special needs, he or she may benefit from a special needs trust to manage their disability-related concerns. 

An older child may make more money than the others leaving the younger children with a greater need for inheritance, or there are situations in which you may wish to completely disinherit an estranged child. Unequal inheritances, however, can lead to numerous problems including ending sibling relationships, will contests, and hurt feelings. if you intend to avoid fighting over children among the different inheritance amounts, it is essential to use trusts instead of wills.

If you pass away with assets in your name alone and only have a will, those assets will go through a probate proceeding. Family conflict with the use of wills is common because children have to receive legal notice with a copy of the will.

Each child may show up in probate court with their own individual lawyer and contest the will. The associated expense and the frustration of litigation can drag on for years. When you use a trust instead of a will, you decrease the chances of family conflict associated with the inheritance. Trusts effectively avoid probate because you transfer assets into the trust while you’re still alive and the trust determines what happens to those assets when you pass away and the children will not necessarily receive legal notice. Consult with an experienced New Jersey estate planning attorney if you would like to discuss this in further detail.

The Threats for Wealthy Families Are on The Rise

Security threats are more prevalent than ever and multi-family offices are being targeted in the most recent round of attacks. According to a recent study, only 9% of all respondents out of 55 family wealth firms were involved day to day in security risk management. Although up to 73% reported recent concerns associating incidents involving their clients.


asset protection planner lawyerA comprehensive asset protection planning approach should always be taken for any wealthy family that is concerned about protecting the wealth they have worked so hard to build. The most prevalent type of financial issue affecting wealthy families, according to the study was credit card fraud.
More than half of the respondents indicated that, at least one of their clients was a victim of credit card fraud in the previous year. Another unsuspecting and yet serious trend has to do with tax returns being hijacked. Given that there are many different ways that high net worth individuals can be targeted, including litigation or a spouse attempting to pursue personal assets as a stake in the divorce, it is extremely important for any high net worth individual to schedule consultation with an experienced asset protection planning attorney to talk over the benefits of advanced planning.

Do You Really Owe Your Kids an Inheritance?

It is never easy to approach the topic of estate planning for anyone. One of the most common reasons that people are uncomfortable with this topic as a whole is that they are concerned that talking about it means reflecting on their own mortality. should you leave behind an inheritance?

This is certainly a challenging act by approaching your estate planning but things can become even more complicated and you may begin to wonder whether or not you owe your children an inheritance and the best ways for leaving behind assets. A recent study conducted by the Insured Retirement Institute indicated that only 46% of baby boomers felt that it was important to leave an inheritance behind to loved ones. In the past, however, that number was closer to the two-thirds rate.

Many people in mid-life expect to spend everything that they have before they pass away; an indication that longevity numbers are certainly having an impact on people’s ability to stretch their retirement income. This also highlights the potentially catastrophic cost of long-term care in health issues.

Planning ahead is key if you do intend to leave behind an inheritance. If you don’t make the proper plans for it, you could be setting up your hires for numerous problems. The state and federal government could end up taking a tremendous amount out in terms of taxes and you could also expose your beneficiaries having this information tapped into by creditors. Leaving behind a legacy is a common goal for many people engaged in the estate planning process and you can accomplish this by consulting directly with an experienced and knowledgeable estate planning lawyer.

Asset Protection Planning: You Need to Have It

Too many people realize that asset protection planning is valuable when it’s too late. For example, after a lawsuit is filed against a doctor or after creditors swoop in to take personal assets. This can expose your entire family, your company, and all that you have worked so hard for to serious risks, and that’s why it’s important to start asset protection planning now, even if you’re not yet sure that you need it. Putting a safeguard plan in place now makes a lot of sense, but you’ve got to be prepared by setting up an initial consultation with an experienced asset protection planning lawyer. If you face risks because of your wealth or your profession, asset protection planning is a must-do. asset protection planning is critical

Looking ahead to the future can increase your chances that your beneficiaries will be able to receive the assets that you intend. More than $59 trillion is expected to pass from baby boomers to the future generation, according to a study published by the Boston College Center on Wealth & Philanthropy. Unfortunately, however, despite these numbers, very few baby boomers have taken steps to ensure that their wealth does not disappear immediately after the transfer. Up to 70% of families lose all of their wealth by the second generation, according to data shared by the Williams Group Wealth Consultancy. 90% of families lose all of their wealth by the third generation.

There are changing needs for affluent and mature clients who are concerned about successfully transferring and preserving their wealth. Identifying an experienced attorney who can assist with the asset protection planning process and infusing various strategies such as trusts and other estate planning tools can give you peace of mind that your assets will be passed on to a future generation and protected as much as possible.


Why Caregivers are So Important for Those Individuals Who Have Disabilities

A 2011 study shared by the Centers for Disease Control and Prevention identified that the number of children who had developmental disabilities increased by 17% between 1997 and 2008. The prevalence of autism alone increased by 290% and attention deficit and hyperactivity disorder increased by 33%. disability estate planning

This expanding portion of the population needs help. Alzheimer’s disease and other cognitive issues may also impact aging parents raising questions about who will be responsible for caretaking and what will happen to an individual’s assets when he or she needs to qualify for Medicaid or additional services. Consulting with an experienced estate planning attorney to discuss future planning for Medicaid and other goals for your assets is extremely important. Many people looking to the future need to consider how a child with developmental disabilities would be cared for.

It is essential that these individuals be able to qualify for government benefits and programs and planning ahead for a sudden asset transfer without taking this into consideration could jeopardize your loved one’s ability to qualify for Medicaid or other benefit programs designed for special needs individuals. Having a conversation well in advance is the best way to plan for this.

Whether it’s a cognitive or a physical disability, the right planning goes a long way. Having a knowledgeable caregiver and plans put in place well in advance can help anyone who is going through the process of protecting the interests of a person with a disability. Talk to an estate planning lawyer today about strategies and options for those with special needs.

Prince’s Estate Still in Limbo One Year Later

Prince passed away just over one year ago. Unfortunately, however, his unexpected death associated with an accidental painkiller is still tied up in probate court. It is estimated that Price’s estate is worth more than $300 million and unfortunately, he passed away without a will and testament to his name, causing serious concerns. This story illustrates just how important basic estate planning can prove to be no matter the size of your estate.NJ estate planning attorneys help you look ahead to the future

Minnesota probate court has had to sift through dozens of dubious alleged claims of a connection to the musician. The courts are still trying to put an end to the ongoing conflicts between numerous family members. Two remaining claimants, however, argue that a temporary special administrator for the estate inappropriately aligned funds that were supposed to be received by beneficiaries.

Prince’s estate shows just how complicated things can get if you do not take the necessary steps to protect your estate well in advance. This can lead to numerous conflicts, allegations from people who are not tied to you at all coming forward and wanting to claim a piece of your estate, and arguments over whether or not an executor is handling things appropriately. Thankfully, as an individual aware of these problems now, you can take necessary steps to minimize the chances that your family will have any additional frustrations or concerns to deal with after you pass away.

The right estate planning lawyer can help you identify next steps in order to accomplish your individual estate planning strategies. Don’t hesitate to contact a lawyer today to learn more about your options.


IRS Changes Process for Estate Tax Liens

One of the aspects of handling an estate that can prove problematic is when the IRS puts a lien on property. The IRS is capable of putting a lien on a piece of property or an asset in order to recover money that is owed to them after a person passes away. 

Internal Revenue Service procedures have been updated in the last several months. No announcement from the IRS was given in June 2016 when the agency consolidated all responsibility for processing form 4422. This paperwork is filed when an estate plan’s transfer assets prior to filing forms 706, if those same assets are a subject to an estate tax lien as outlined under internal revenue code section 6324. Obtaining a lien release after filing a form was a routine matter in the past.

However, the IRS has been mandating that all of the net proceeds from the sale of that property be put into an escrow account or the estate tax account directly with the IRS. The IRS issued a statement earlier in 2017 acknowledging that they were reviewing and updating their process. A memorandum was issued on April 5th about the internal guidance for processing requests and discharging the estate tax liens. If you have concerns about qualifying for the estate tax and strategies and steps you can take, as well as how it may affect your future beneficiaries, consult with a knowledgeable estate planning attorney today.


How to Use Your Will to Assist Your Elderly Parents

Many individuals are looking forward to the future and the future generations when it comes to putting together a will and other components of an estate plan. However, you may also be interested in putting together an estate plan and in particular, your will to assist your elderly parents. Although no one wants to think about their own mortality, it can be important to consider all potential opportunities for estate planning well in advance. 

If you were to pass away in advance of your parents, your parents could struggle significantly. A will could assist your elderly parents from avoiding government benefits in the event that you passed away before they did. For example, if your parents were listed as the beneficiaries on a life insurance policy, a large payout from the life insurance company could make it impossible for your parents to qualify for the government benefits they need through Medicaid, unless you have a critical provision listed inside your will.

If your parents have limited resources and were planning on receiving Medicaid to assist them with their health care concerns in older age, you may need to take additional steps to consult with an experienced estate planning attorney about the best way to approach holistic estate planning.

Holistic estate planning should view not only what happens to your assets after you pass away, but how your individual beneficiaries will be impacted by such a move. This allows you to come out with strategies and tactics that can assist with making the transfer of assets as complementary to everyone as possible.

New BMO Wealth Management Report Shows That There Are Complicated Family Dynamics for Estate Planning

A new study indicated that up to one-quarter of married adults shared that only their spouse understood the location of their power of attorney and the wills. That survey also indicated that less than 30% of adults knew the location of their parents’ wills or details about the estate distribution plans or executor selections.

It turns out that families with significant wealth may have a long way to go in order to effectively discuss estate planning. Family dynamics are becoming more complex, making it more likely than ever that there will be a conflict after somebody passes away. 40% of the individual surveyors felt that the current distribution plans for their parents’ estate were unfair. Unmarried respondents were those individuals most likely to indicate this. Several financial planning tips can assist you with ensuring that you have minimal conflict opportunities with your loved ones. These include:

  • Setting up a meeting to discuss tax implications.
  • Using a trust to transfer assets outside of your estate.
  • Reviewing your will on a regular basis to ensure that it is updated.

If you have questions about the estate planning process and how it can be used to help you contact an experienced estate planning lawyer today.


Two Part Post on Real Estate and Your Estate: Part Two

In general, probate refers to the legal proceedings by which your assets are analyzed and then distributed by the court. Everything that you own, including your land is distributed according to the New Jersey intestate statutes. It can take up to one year for a probate case to make its way through the court system and it can also be extremely expensive as a result of this delay and the costs of an estate attorney. Probate is also a very public process which is one of the primary reasons that if you intend to pass on real estate to your loved ones, you should do so by using a will, trust, or other estate planning tool. real estate probate

Consulting with a lawyer sooner rather than later will give you a broad overview of all the things you need to consider in the estate planning process for your real estate. If you have a vacation property or a primary home, the most important question to ask is whether or not it is designated as tenancy-in-common or joint tenancy. In a joint tenancy situation, two individuals own the property with equal shares. This means that if one person passes away, the ownership of the property is automatically transferred to the other owner without a will. This is classified as right of survivorship. All that is necessary in order to retain ownership is to get a copy of the death certificate recorded for the deceased joint tenant.

Common tenancy, on the other hand, means that two or more individuals own a property in varying portions. Joint tenancy means that equal shares are maintained by individuals at the same time but common tenancy can occur where owners are added or removed from the property’s co-ownership.

Tenants-in-common do not have survivorship rights unless the deceased’s will classifies that his or her interest in such a property is to be divided amongst surviving owners. Otherwise the share of the property goes to his or her real estate and a will can direct where that share will go. After an individual inherits a property, he or she is subject to whatever mortgage exists. That person needs to put together a will as quickly as possible in the event that he or she were to become incapacitated or pass away. The heir can then choose to sell or to keep the property.


A Two-Part Series on Your Estate Plan and Real Estate

Planning ahead for what will happen to your property after you pass away is an important venture and one that should be done under the guidance of an estate planning attorney. Most people don’t want to broach the subject of estate planning as it relates to their real estate but it is extremely important to discuss what will happen to your property if you were to become incapacitated or pass away.NJ estate planning

Managing your final wishes can be extremely challenging for loved ones in this situation. It is strongly recommended that you put together a will to pass down any real estate. The intestate statute in New Jersey will automatically pass down your land and other assets to your closest relatives in accordance with the laws. However, if you want the land to go to a particular individual or to stay together, then it is necessary to write a will. There are other situations in which it might make the most sense to put together a will for estate planning purposes. You might not want certain heirs to inherit particular assets.

Without a will you will not be able to determine where you want the property to go instead of to unfavored relations. If you do not have any children and do not plan to in the future, you can select siblings, nephews, nieces or charities as your beneficiaries but you may want to have primary and contingent beneficiaries that can help you ensure that certain individuals do not profit from your estate. In the event that you do not have a will, an individual’s estate is classified in New Jersey as intestate and enters the official probate process.

Millennials Share Their Unique Retirement Planning Interests

Research shows that Generation Y hopes to plan for retirement online as well as on mobile and they would prefer to do so with all the help they can get. This indicates an important societal shift that could occur as it relates to retirement planning and estate planning. 

Although millennials are typically defined as a generation focused on individuality, many of them recognize that they need assistance managing their finances and planning ahead for retirement. Most millennials are asking for their employer’s help, for example, in selecting the right investments.

Up to 69% of millennials in fact stated in a recent study that they would like to outsource the management of their retirement portfolio. This provides an important connection to the estate planning process as well. Since more millennials are interested in handling things online and easily, it’s an important conversation that needs to incorporate estate planning as well.
While millennials might often fall into the myth of thinking that they do not need estate planning services since they are relatively young and healthy, that is incorrect. Important documents like a power of attorney can help empower millennials to make critical decisions.  

Do You Really Need to Pay an Estate Planning Lawyer to Assist You?


There are plenty of times in life when it makes sense to handle things on your own or to avoid spending money that you simply do not have or do not need to spend to accomplish a goal.


While there are numerous different examples when it does make sense to avoid hiring a professional to assist you, estate planning is not one of them. Paying a professional to assist you with the estate planning process is a good way to give you peace of mind that all possible questions and concerns have been addressed and to ensure that your estate plan is legally valid and accurate.


In the event that you make small mistakes trying to handle things on your own, this might not affect you, but it will most certainly effect your loved ones named in the estate planning document. If you make a mistake, for example, or do not clearly articulate what you intend to happen to your assets, it may be more challenging for your loved ones to interpret this. This also means that there is a good chance that your estate will have to go through the probate process, further complicating an already difficult situation.
Thankfully, sitting down with an experienced professional gives you the peace of mind that comes with knowing that someone has thoroughly reviewed your individual estate plan and has made recommendations for you that help to target the passing on of assets, planning for your estate while you are still alive, determining who will step in as guardian for your minor children and minimizing any potential taxes. Consult with a lawyer now to get the benefit of working with a professional.

It’s Essential to Connect Personal Estate Planning and Business Succession Planning for Business Owners

According to data from the U.S. Census Bureau, in 2012, there are 27.6 million businesses closely held in the United States. Business ownership and entrepreneurship are critical drivers of legacy creation as well as significant wealth, but it becomes even more important for the individual to approach estate planning from their personal perspective as well their business. 

Owners of closely held businesses should commit to succession planning and looking ahead for exit strategies as well as estate planning as well. Up to 80% of business owners, according to research conducted by the Family Business Institute, indicated that they will be able to pass their company on to the next generation.
However, business succession statistics actually show that there is a decrease in business survival. Up to 64% of business owners in 2015, did not have any business succession plan at all, putting their family’s greatest source of security and wealth at risk. You need to consult with an experienced business succession planning attorney as soon as possible to identify all of the opportunities to minimize your risk and this includes looking at succession planning and exit strategies as well.

Americans are Passing Away Within an Average of $62,000 of Debt

There is a good chance that you may pass away with some debts in your name. In fact, a recent study conducted by credit.com, identified that 73% of consumers have outstanding debt that was reported after they passed away. Those consumers carried an average balance of $12,875 in debt not associated with a mortgage. For an individual who had a mortgage, the debt was $61,554. 

More than 220 million consumers had their data crunched for this particular study. Among the 73% of consumers who passed away with debt, approximately 70% of them had credit card balances. The next most frequent kind of debt was a mortgage debt at 37% followed by auto loans, personal loans, and student loans. When you pass away, your debt may still affect the people that you leave behind. Debt belongs to a deceased individual or the deceased person’s estate.

In the event that there are enough assets to cover these debts, creditors are paid and then beneficiaries receive whatever is left afterwards. If there are not enough assets to satisfy debts, then creditors will lose out. There are many different ways that things can get messy in this process. It’s important to consult with an experienced estate planning attorney to understand how debt may influence your estate.


Would a Domestic Asset Protection Trust Work for You?

Have you ever heard of a domestic asset protection trust? This is a tool in which you create a trust inside a U.S. jurisdiction in order to protect the person who is putting together the trust. One aspect that makes these different is that the person who creates the trusts and put assets into it is usually a beneficiary of the trust so that that person still gets the economic rewards of the assts placed into the trust. This can also guard against outside creditor claims, a primary reason why people want to engage in asset protection planning in the first place. 

There are many different reasons why you might want to take advantage of this type of trust. First of all, if you have a high net worth, you may want to remove the assets from being so closely connected to your individual assets in the event of a creditor claim. You might also be concerned about litigation risks that could expose your assets to judgments. These are two of the most common reasons why a personal will set up a meeting with an estate planning lawyer to walk through domestic asset protection trusts. There are several groups of people more likely to be targeted in lawsuits, including attorneys, officers and directors of public companies, and doctors. Often this is part of a bigger estate planning goal and can minimize fears about your personal assets being tapped by creditors or by lawsuits.

You might also have a person in your family who you would classify as a spendthrift or a person with disabilities. These kinds of trusts can be valuable tools for orchestrating the transfer of assets while giving the creator some peace of mind and comfort in knowing that all unique concerns have been considered.